Blog

  • Gold IRA Fees and Red Flags: What to Demand in Writing

    Gold IRA Fees and Red Flags: What to Demand in Writing

    GOLD IRA · FEES · RED FLAGS
    • Annual precious metals IRA charges include custodian ($75–$300) + storage ($100–$300) + insurance = $300–$600+ per year minimum, before transaction costs.
    • Dealer spreads on metal purchases typically run 3%–8% above spot price—meaning you lose 3%–8% of principal on day one before the market moves.
    • The industry has a documented history of deceptive marketing: free storage promotions that end after year one, hidden buyback costs, numismatic coins sold as IRA-appropriate at 15%–100% markups.
    • A $100,000 account with 1% annual charges underperforms the same amount in a gold ETF by approximately $73,000 over 20 years, assuming identical price performance.

    The Complete Gold IRA Fee Structure: Every Charge That Exists

    Gold IRA charges are often presented opaquely—companies emphasize one cost while burying others in fine print, or advertise promotions that expire after the first year. The industry has been subject to regulatory action and consumer complaints specifically related to fee transparency. Before opening any precious metals IRA, obtain a complete schedule of charges in writing and calculate your total annual cost as a percentage of your planned account balance.

    Gold IRA Fee Categories: Typical Ranges and What to Watch
    Fee Type Typical Range When Charged Watch Out For
    Account setup $50–$300 one-time At account opening Some companies waive this, then raise annual fees or sell metals at inflated premiums
    Annual custodian $75–$300/year Ongoing Flat vs. percentage—percentage fees grow as your balance grows
    Storage (segregated) $150–$300/year Ongoing Your specific bars/coins stored separately; more verifiable but pricier
    Storage (commingled) $100–$150/year Ongoing Mixed with other clients’ metals; you get equivalent units, not your specific coins
    Insurance $50–$100/year or bundled Ongoing Confirm coverage amount and the name of the insurer
    Transaction fee (purchase) $40–$100 per transaction When buying metals Added on top of the dealer spread; may apply per metal type
    Transaction fee (sale) $40–$100 per transaction When selling Applies when funding RMDs or closing the account
    Wire transfer $25–$50 per wire Each transfer in or out Adds up across multiple contributions or distributions
    Buyback fee 0%–5% of value When selling back to dealer Always compare dealer buyback price to current spot price
    Termination/closure $100–$250 At account close Some companies charge to ship metals out or transfer to another custodian

    The combination that matters is annual custodian + storage + insurance = baseline annual drag. On a $50,000 account, $500 per year is 1.0% annually. Flat charges disproportionately hurt smaller accounts: that same $500 annual cost on a $25,000 account is 2.0% per year—a significant headwind before the dealer spread on initial purchase is even counted. Percentage-based charges hurt larger accounts more as balances grow. Confirm the structure type before opening.

    The Dealer Spread: Losing Money Before the Market Moves

    The dealer spread is the markup above daily spot price that you pay when purchasing physical metals. It is not a line-item charge that appears on a statement—it is the gap between what you pay and what the bullion is worth at that exact moment in the open market. On a $50,000 purchase with a 5% spread, you have effectively lost $2,500 of purchasing power before the metal is even stored. The price must then rise at least 5.26% before you are back to even.

    Spread size varies significantly by product type and dealer. Bars from major refiners such as PAMP Suisse and Credit Suisse typically carry lower premiums than coins, which carry premiums for their design and legal tender status. Numismatic and collectible coins carry the highest markups—sometimes 15%–100% or more above spot—and those markups are rarely recovered at resale. Always ask for the per-ounce purchase price and the current spot price before committing to any transaction.

    Dealer Spread Impact on a $50,000 Gold Purchase
    Dealer Spread Your Purchase Price Immediate Paper Loss Gold Must Rise This % to Break Even
    3% $51,500 $1,500 3.09%
    5% $52,500 $2,500 5.26%
    8% $54,000 $4,000 8.70%
    15% (numismatic) $57,500 $7,500 17.65%
    Ask for a quote showing the per-ounce price and today’s spot price before any purchase. Divide the difference by spot—that is your spread. A dealer who will not show you this math is a dealer to avoid.

    Nine Red Flags in Gold IRA Marketing and Sales

    The precious metals IRA industry includes legitimate, transparent companies and predatory ones. The FTC and SEC have each brought enforcement actions against precious metals dealers for fraud, misleading claims, and deceptive pricing practices. The following red flags are documented patterns from regulatory actions and consumer complaints—not theoretical risks.

    1. “Free Storage for Life” or “First Year Free” Promotions

    Free introductory storage is a marketing expense recovered elsewhere. Companies offering free first-year vault costs typically offset it through higher ongoing charges in subsequent years, inflated metal premiums at purchase, or custodian referral arrangements that are not disclosed. The relevant figure is not what year one costs—it is total expense over your actual holding period. Request a complete 5-year cost projection, including storage, custodian, insurance, and any transaction charges for the purchase and eventual sale, before evaluating any promotional offer.

    2. Selling Numismatic or “Rare” Coins as IRA Investments

    Rare and collectible coins carry premiums of 15%–100% above their gold content value. Salespeople commonly pitch these coins as better performers in economic crises—claiming that collectors pay premiums during downturns that amplify returns. There is no credible peer-reviewed evidence supporting this claim. In practice, numismatic value is driven by collector markets that behave independently of spot bullion prices. More critically, collectible coins are generally prohibited from IRAs under IRS rules. A company selling a coin whose bullion content is worth $1,800 but whose asking price is $3,000 is collecting a 67% markup while potentially selling you an IRS-prohibited asset.

    3. “Home Storage IRA” Offers

    Any company suggesting that you can legally store IRA bullion at home, in a personal safe, or in a personally controlled LLC is either uninformed about current law or deliberately misleading you. The U.S. Tax Court ruled home storage of IRA-held metals illegal in McNulty v. Commissioner (2021). The full account balance—not just the removed metals—becomes a taxable distribution in the year home storage begins. Walk away from any company marketing this structure regardless of how it is legally packaged.

    4. Guarantees of Performance

    No legitimate investment professional guarantees investment returns on any asset, and precious metals are no exception. The metal fell more than 40% between September 2011 and November 2015—a decline that lasted more than four years. Any marketing material guaranteeing that bullion will rise in value, promising “crisis-proof” returns, or suggesting it never loses value is factually false. Guarantees of performance are a violation of securities regulations when made by registered advisors and a material misrepresentation when made by anyone else.

    5. High-Pressure Tactics and Urgency Claims

    “This offer expires today” is a sales manipulation tactic, not a reflection of market reality. Gold spot prices are publicly available every second the market is open, and they change continuously. There is no legitimate reason a gold IRA promotion would expire today rather than tomorrow. Urgency claims are designed to prevent you from reading the documents, comparing competitors, or consulting an advisor. Any salesperson pressuring you to decide before you have reviewed written materials is a salesperson to walk away from.

    6. Commission-Paid “Educational” Content

    Much of the content promoting gold IRAs—online articles, radio programs, television endorsements, podcast sponsorships, and celebrity recommendations—is paid advertising presented as independent educational material. Political commentators, media personalities, and entertainers are compensated to endorse specific gold IRA companies, and this compensation is frequently in fine print or not disclosed at all. Before trusting any recommendation for a specific gold IRA company, determine whether the person recommending it receives compensation from that company. If the answer is yes, the recommendation is an advertisement, not independent analysis.

    7. Refusal to Provide the Full Schedule Before You Sign

    A reputable custodian provides a complete, written schedule of charges before account opening—not after. If costs are described as “depending on your account size” without a specific formula, or if you are told that storage charges “vary” without a defined rate, that is not transparency. Get every item—setup, annual custodian, storage type (segregated or commingled), insurance, transaction charges, wire charges, buyback costs, and termination costs—in writing before signing any agreement. If a company resists providing this, the annual total is likely higher than they want you to calculate in advance.

    8. Pressure to Move Your Entire 401(k) Into Precious Metals

    No credible, independent financial advisor recommends concentrating 100% of retirement assets in bullion. The metal is a non-income-producing asset—it pays no dividends, generates no interest, and produces no cash flow. It is volatile: a 40% decline over four years is historical fact, not hypothetical risk. The annual cost drag described throughout this article compounds significantly over a 20-to-30-year retirement horizon. Legitimate precious metals allocations within a diversified retirement portfolio are typically cited in the 5%–15% range. Any salesperson suggesting your entire retirement should be in physical metal is optimizing for their commission, not your outcome.

    9. The Custodian and Dealer Are the Same Entity

    The IRS requires a qualified custodian to hold retirement account assets separately from the dealer who sells the metals. When one company controls both functions, it profits twice: from selling you metals at inflated prices and from holding your account. That dual role creates a structural conflict of interest—the company that benefits from higher purchase prices is also the entity responsible for safeguarding your balance. Use an independent custodian that has no financial relationship with the metals dealer, and confirm this independence before opening an account.

    Gold IRA vs. Gold ETF: The 20-Year Cost Comparison

    Both a physical precious metals IRA and a gold ETF held in a conventional IRA track the price of bullion. Price appreciation before charges is functionally identical in both structures—both rise and fall with spot prices. The material difference is cost structure, and over a 20-year horizon the cumulative impact on ending balance is substantial.

    A gold ETF such as iShares Gold Trust (IAU) carries an annual expense ratio of 0.09%—meaning on a $100,000 position, annual cost is $90. The SPDR Gold Shares ETF (GLD) charges 0.25%, or $250 per year. There are no setup costs, no storage costs, no insurance charges, no dealer spread on purchase, and no transaction charges at most brokerages. A precious metals IRA with $500 in annual charges costs 5.5 times as much as IAU and 2 times as much as GLD on the same balance—before accounting for the initial dealer spread.

    Gold IRA vs. Gold ETF in a Regular IRA: 20-Year Comparison ($100,000 Starting)
    Factor Gold IRA (Physical) Gold ETF in Regular IRA
    Annual expense ratio None 0.09%–0.25% (IAU or GLD)
    Annual custodian + storage fees ~$500/year flat $0
    Initial dealer spread $3,000–$8,000 $0
    Transaction fees $50–$100 per trade $0 most brokerages
    Est. 20-year fee drag $15,000–$25,000 + spread $1,800–$5,000 ETF ratio only

    The counterargument from physical bullion advocates is valid in certain scenarios: ETFs carry counterparty risk—the fund’s assets depend on the ETF structure and its custodian—and physical metal has intrinsic value that exists independent of any financial institution. Those are real distinctions, not marketing claims. But for most retirees whose goal is price exposure within a retirement account, the ETF achieves the same return profile at 10%–20% of the annual cost of a physical precious metals IRA. Make the decision with full knowledge of that cost gap.

    Six Questions to Ask Before Opening a Gold IRA

    1. What is the complete schedule of charges including custodian, storage, insurance, transaction costs, and termination cost? Demand in writing.
    2. What is your current dealer spread on the products I am considering? Ask for the per-ounce price and today’s spot price.
    3. Who is the custodian, and is it a separate entity from the dealer?
    4. Which IRS-approved depository will hold my metals, and can I verify my holdings online?
    5. What is your buyback policy, and what price do you pay versus spot?
    6. Are you compensated by any third party for recommending specific products?

    The 60-Second Red Flag Checklist

    • ⚠ If a company offers “free storage for life” or “first year free” → The cost is recovered elsewhere — in higher ongoing charges, inflated metal premiums, or undisclosed custodian referral arrangements. Request a complete 5-year cost projection before evaluating any promotional offer.
    • ⚠ If a salesperson recommends numismatic, rare, or collectible coins → These carry markups of 15%–100% above their bullion content value, and collector markets behave independently of spot prices. Most are also IRS-prohibited in a retirement account. Any seller promoting these is collecting a large markup, possibly on an ineligible asset.
    • ⚠ If a company markets a “home storage IRA” or “checkbook IRA” for physical precious metals → This arrangement was ruled illegal by the U.S. Tax Court in McNulty v. Commissioner (2021). The full account balance becomes a taxable distribution in the year home storage begins. Walk away regardless of how it is packaged.
    • ⚠ If any marketing material guarantees performance or calls the asset “crisis-proof” → The metal fell more than 40% between 2011 and 2015 over four years. Performance guarantees are false and, when made by registered advisors, a regulatory violation. They signal you are talking to a salesperson optimizing for commission.
    • ⚠ If there is pressure to decide today or the offer “expires” → Spot prices are public and change continuously. There is no legitimate reason an offer expires today rather than tomorrow. Urgency tactics are designed to prevent you from reading documents or comparing competitors. Any deadline pressure is a reason to slow down, not speed up.
    • ⚠ If the company will not provide a complete written schedule before you sign → Get every item in writing — setup, annual custodian, storage type (segregated or commingled), insurance, transaction costs, wire costs, buyback costs, and termination costs. A company that resists this disclosure likely has annual charges higher than they want you to calculate in advance.
    • ⚠ If the custodian and the dealer selling you metals are the same entity → The IRS requires these roles to be separate. One company controlling both profits twice — from selling metals at inflated prices and from holding your account. That dual role creates a structural conflict of interest. Use an independent custodian with no financial relationship to the dealer.
    • ⚠ If a salesperson recommends moving your entire 401(k) or IRA into precious metals → No credible independent advisor recommends 100% concentration in bullion. The metal produces no income and is volatile. Legitimate allocations within a diversified portfolio are typically cited in the 5%–15% range. A recommendation to put everything in physical metal is optimizing for commission, not your retirement.

    For context on benchmarks: a reputable precious metals IRA with flat costs should run $300–$600 per year total for custodian, storage, and insurance combined. A dealer spread below 3% on bars from major refiners is reasonable; anything above 5% warrants comparison shopping. The comparison point is always a gold ETF such as IAU at 0.09% annually — on a $100,000 account, that is $90 per year versus $500 for a typical physical precious metals IRA. The physical account has real advantages — no counterparty risk, tangible asset ownership — but those advantages must be weighed honestly against an annual cost structure that is 5 to 10 times higher over a multi-decade holding period.
    Honest boundary: Gold IRA companies range from transparent and reputable to actively deceptive. The FTC and SEC have brought enforcement actions against precious metals dealers for fraud and misleading claims. Before committing retirement funds, verify claims independently and consider a fee-only advisor who receives no commissions from metal sales. This is not financial, legal, or tax advice.
  • Best States for a Gold IRA in 2026: Tax, Storage, and Legal Shield

    Best States for a Gold IRA in 2026: Tax, Storage, and Legal Shield

    GOLD IRA · STATES · 2026
    • Nine states have no personal income tax — zero state-level levy on retirement distributions, including from a precious metals IRA.
    • Fourteen-plus states have passed sound money laws recognizing gold and silver as legal tender or eliminating sales tax on bullion.
    • Creditor coverage for retirement assets varies dramatically — Texas, Florida, Nevada, South Dakota, and Wyoming offer unlimited insulation; California’s standard is the weakest.
    • The best jurisdiction for a precious metals IRA holder combines all three factors: no income tax, bullion sales tax exemption, and unlimited statutory shield from creditors.

    Why Your State of Residence Matters for a Gold IRA

    Federal law governs the structure of your gold IRA — contribution ceilings, transfer rules, required minimum distributions, IRS-approved custodians, and approved storage facilities are uniform across all 50 states. What federal law does not control is how your jurisdiction treats you as a precious metals IRA holder. Three areas of state law have real financial consequences: income tax on distributions, sales tax on bullion purchases, and creditor coverage for retirement assets.

    The income tax difference alone can be substantial. Consider a $300,000 precious metals IRA taking $20,000 per year in distributions during retirement. In California, where the top marginal rate reaches 13.3%, that distribution could generate $2,660 in state income levy annually — $26,600 per decade. In Texas, with no income tax, the same distribution generates $0 in local taxes. Over a 20-year retirement, the difference is more than $50,000, not accounting for inflation adjustments or rate changes.

    Creditor coverage matters most for professionals who carry litigation exposure — physicians, attorneys, business owners, and contractors. A judgment against you in most states can reach retirement assets to satisfy a debt, but the extent of statutory insulation varies from unlimited to essentially none. For large precious metals IRA balances, understanding your state’s legal shield before a dispute arises is far more valuable than understanding it after.

    The Nine No-Income-Tax States: Zero Tax on Gold IRA Distributions

    States With No Personal Income Tax
    State Income Tax Notable Notes
    Alaska None Annual Permanent Fund dividend; no sales levy either
    Florida None Large retiree population; no inheritance levy
    Nevada None Strong asset safeguard laws; popular for trusts
    New Hampshire None Dividend and interest levy fully eliminated effective 2025
    South Dakota None Strong creditor coverage; no inheritance levy
    Tennessee None Fully eliminated income levy in 2023
    Texas None No estate levy; unlimited IRA creditor shield
    Washington None on wages and distributions 7% capital gains levy enacted — IRAs exempt from that levy
    Wyoming None Strong sound money legislation; no estate levy

    For precious metals IRA holders specifically, Washington’s capital gains levy deserves attention. Retirement distributions are taxed as ordinary income, not capital gains, so they are unaffected by Washington’s 7% levy. Bullion held outside a retirement fund — physical metals in a personal account — would face that tax on any appreciation upon sale, which is a meaningful distinction for investors who hold precious metals both inside and outside tax-advantaged holdings.

    Sound Money States: Where Bullion Is Sales-Tax Free

    The sound money movement has eliminated sales tax on precious metals bullion in many states, reflecting a policy position that gold and silver function as money rather than taxable consumer goods. For precious metals IRA holders, this primarily affects two situations: the initial purchase of metals and any in-kind distributions taken at retirement. The dealer’s location, your state of residence, and the depository’s location can all interact in determining sales tax exposure.

    Inside a functioning self-directed precious metals IRA, the custodian purchases bullion on your behalf, and the depository location may matter more than your home state. But when you take an in-kind distribution — receiving physical coins or bars rather than cash — the sales tax treatment of that event in your state of residence becomes relevant. Confirm the specifics with the custodian and a tax professional familiar with your jurisdiction.

    Selected States With Sound Money Legislation (2026)
    State Sales Tax on Bullion Legal Tender Status Notable Provisions
    Texas Exempt Bullion Depository established by the state State-chartered depository; accepted for official transactions
    Utah Exempt Legal tender recognized First state — Legal Tender Act 2011
    Wyoming Exempt Legal tender recognized Strong overall precious metals framework
    Arizona Exempt Legal tender law passed Income from gold/silver legal tender not taxed by the jurisdiction
    Idaho Exempt Sound money recognition Capital gains on gold and silver exempt from local levy
    Montana No general sales levy Legal tender recognition No sales charge on any purchases
    New Hampshire No general sales levy Legal tender recognition No income levy; no sales charge

    IRA Creditor Protection by State: What a Judgment Could Take

    Federal ERISA law provides robust exemption from creditor claims for employer-sponsored retirement plans, including 401(k) accounts — most creditors cannot reach ERISA plan assets regardless of which state you live in. Self-directed retirement accounts, however, receive federal coverage only in bankruptcy proceedings (approximately $1.5 million per person, indexed to inflation for subsequent adjustments). Outside of bankruptcy, IRA creditor insulation is entirely governed by state law, and the variation between jurisdictions is dramatic.

    The practical implication: if a creditor wins a judgment against you in civil court and you are not in bankruptcy, your state’s statute determines whether the fund is reachable. A physician in California with a $500,000 precious metals IRA faces meaningful exposure. The same physician who has established residency in Texas faces none.

    State IRA Creditor Protection Comparison
    State IRA Protection Notes
    Texas Unlimited All IRAs shielded from all creditors except IRS and domestic support obligations
    Florida Unlimited IRAs explicitly exempt from creditor claims
    Nevada Unlimited Strong trust and asset safeguard laws complement retirement fund coverage
    South Dakota Unlimited One of the strongest asset-insulation frameworks in the country
    Wyoming Unlimited Retirement assets fully exempt from creditor claims
    New York Unlimited for IRAs Statutory exemption is strong; verify type of account
    Illinois Up to $1,000,000 Strong but capped; also no income levy on retirement distributions
    Ohio Up to $500,000 Capped coverage; may be insufficient for large gold IRA balances
    California “Necessary for support” only Courts determine necessary support; large balances may be exposed

    California’s standard is the most dangerous for high-balance IRA holders. A creditor can argue that a $500,000 precious metals IRA is more than you “need” for support, and California courts make that determination case by case with no statutory ceiling. For professionals with meaningful litigation exposure living in California, this is one of the strongest financial arguments for establishing domicile elsewhere before a legal dispute arises.

    The Top States for Gold IRA Holders: Combined Score

    Best States for Gold IRA Holders — All Three Factors
    State Income Tax on Distributions Bullion Sales Tax IRA Creditor Protection Overall Rating
    Texas None Exempt Unlimited Excellent
    Wyoming None Exempt Unlimited Excellent
    Nevada None Partial exemptions Unlimited Very Good
    Florida None Not exempt Unlimited Very Good
    South Dakota None Partial Unlimited Very Good
    New Hampshire None No sales tax Strong statutory Good
    Arizona 2.5% flat Exempt Moderate Good for sound money

    Texas stands out because it scores on all three dimensions simultaneously and has a state-chartered precious metals depository — the Texas Bullion Depository — which is an IRS-qualified storage facility within the state. Precious metals IRA holders in Texas can store their metals at an in-state, IRS-approved facility, pay no state income levy on distributions, pay no sales tax on bullion, and hold retirement assets entirely shielded from creditors outside of the IRS and domestic support obligations.

    State Income Tax Rate Comparison NV TX FL NY CA 0% 0% 0% 10.9% 13.3% Top marginal income tax rate by state (retirement distributions)

    Moving to a Better State: What Actually Changes

    Relocating for financial or legal-insulation reasons is entirely legal and increasingly common among retirees and high-net-worth individuals. The concept is straightforward: establish genuine domicile in the new location, and that jurisdiction’s laws govern your obligations and asset coverage. The retirement fund itself does not move — it remains with the same custodian and depository regardless of where you live. Your location of residence at the time of each distribution determines which jurisdiction claims that amount.

    The practical challenge is proving domicile change. California in particular aggressively audits former residents who claim to have moved. California’s Franchise Tax Board uses a multi-factor test: the number of days spent in each location, vehicle registration, driver’s license and voter registration, location of primary residence, social and professional ties, and where medical care is received. Moving to Nevada while spending six months a year in a California vacation home is not a genuine domicile change and will not survive audit. A true move requires transferring the center of your life — not just renting a mailbox.

    The year of the move creates additional complexity. Partial-year residency means income earned or distributed while a California resident is taxable by California, and income earned or distributed after establishing Nevada residency is not. This split-year calculation requires careful record-keeping and often a CPA who handles multi-jurisdiction returns. Plan the timing of any large retirement distributions around your move date and consult a professional well in advance.

    Action Checklist

    1. Identify your jurisdiction’s rate on retirement distributions — many jurisdictions with income taxes also exempt some or all retirement income; check your Department of Revenue website for the current exemption threshold.
    2. Check your jurisdiction’s bullion sales exemption — confirm whether it applies to coins, bars, or both, and whether there is a minimum purchase threshold that affects your situation.
    3. Research your jurisdiction’s retirement asset legal-shield statute by name — your local bar association or an estate planning attorney can confirm current coverage levels and any recent court interpretations.
    4. If considering relocation for financial or legal-insulation reasons, consult a multi-jurisdiction attorney or CPA before moving — the year of the move creates partial-year residency complications that require professional planning.
    5. Verify where your precious metals IRA depository is located — most are in Texas, Delaware, or Utah; if you live in a jurisdiction with bullion sales levies, ask the custodian whether the depository location affects your obligations on in-kind distributions.
    Honest boundary: Laws change frequently. Several jurisdictions added or modified sound money legislation between 2022 and 2026. Creditor exemption statutes have been amended by legislation and court interpretation. Verify specific statutes with current sources and consult a licensed attorney in your location before making relocation or asset-safeguard decisions. This is not legal, financial, or investment advice.
  • 401(k) to Gold IRA Rollover: IRS Rules, Costs, and What to Avoid

    401(k) to Gold IRA Rollover: IRS Rules, Costs, and What to Avoid

    GOLD IRA · ROLLOVER · 2026
    • A direct transfer from a 401(k) to a Gold IRA is tax-free when the check goes to the new custodian—never to you personally.
    • IRS requires gold to be at least 99.5% pure, silver 99.9%, platinum and palladium 99.95%—most collector and numismatic coins do not qualify.
    • Home storage of IRA-held bullion is illegal per Tax Court 2021 (McNulty v. Commissioner)—the full IRA balance becomes a taxable distribution in the year home storage begins.
    • Annual charges typically run $300–$600 including custodian, storage, and insurance—compared to $0 for a gold ETF held in a regular brokerage account.

    What Is a Gold IRA and How Does It Differ From a Regular IRA?

    A self-directed Gold IRA holds physical bullion rather than stocks, bonds, or mutual funds. Unlike a standard brokerage account, this type of IRA requires two separate entities: an IRS-approved custodian—typically a specialized trust company rather than a conventional bank or broker-dealer—and an IRS-approved depository where the physical holdings are stored. You cannot take personal possession of the bullion while it remains a retirement asset.

    The same fundamental tax rules that govern conventional retirement plans apply to a Gold IRA. A traditional Gold IRA receives pre-tax contributions, allowing you a potential deduction in the year of contribution, and distributions in retirement are taxed as ordinary income. A Roth version receives after-tax contributions with no deduction, but qualified distributions in retirement—including any appreciation in the value of the metal—are entirely exempt from tax. Contribution limits, required minimum distribution rules, and transfer rules are identical to those for standard IRAs.

    How to Roll Over a 401(k) to a Gold IRA Without Paying Tax

    There are two methods for moving money from a 401(k) into a self-directed Gold IRA. A direct rollover is the recommended method: your 401(k) plan administrator sends the funds directly to the new custodian, never passing through your hands. No mandatory withholding is applied, there is no 60-day deadline to meet, and there is no risk of an accidental taxable event. This is the cleanest and safest approach for virtually all investors.

    An indirect rollover works differently and carries meaningful risk. Your 401(k) plan issues a check made out to you for the distribution amount, but first withholds 20% for federal income tax. You then have 60 days to deposit the full pre-withholding amount—including the 20% that was withheld—into your new IRA. To avoid a taxable event, you must replace that withheld 20% out of your own pocket. If you cannot replace it, the portion not deposited is treated as a taxable distribution and subject to ordinary income tax plus, if you are under 59½, a 10% early distribution surcharge.

    Warning: If you take an indirect rollover and miss the 60-day deadline, the entire distribution becomes taxable income—plus a 10% early distribution surcharge if you are under 59½. One extension may be available but is not guaranteed. Always use a direct transfer.

    IRS Purity Standards: Which Metals Actually Qualify for a Gold IRA

    The IRS sets minimum purity standards for bullion held in a self-directed retirement IRA. Most coins sold in the collectibles market—including many well-known bullion coins—do not meet these standards and are prohibited. Before purchasing any bullion for your self-directed IRA, confirm with the custodian that the specific product qualifies.

    IRS-Approved Precious Metals for Self-Directed IRAs
    Metal Minimum Purity Approved Examples Not Approved
    Gold 99.5% American Gold Eagle, Canadian Maple Leaf, PAMP Suisse bars, Credit Suisse bars South African Krugerrand (91.67%), most numismatic and collector coins
    Silver 99.9% American Silver Eagle, Canadian Maple Leaf, .999 bars from approved refiners Sterling silver, junk silver coins
    Platinum 99.95% American Platinum Eagle, Canadian Maple Leaf platinum Coins below 99.95% purity
    Palladium 99.95% Canadian Maple Leaf palladium, PAMP Suisse palladium Most other palladium products
    Exception: American Gold Eagle coins are 91.67% gold but are explicitly IRS-approved due to their legal tender status. They are one of the few coins below 99.5% that qualify. Always confirm specific products with the custodian before purchasing.

    Home Storage Gold IRAs: Why They Are Illegal and What Happens If You Try

    The U.S. Tax Court ruled definitively in McNulty v. Commissioner (2021) that storing IRA-held bullion at home or in a personal safe constitutes a prohibited transaction under the Internal Revenue Code. The ruling rejected the argument that an IRA holder could use a single-member LLC to take constructive possession of the gold and store it at home. The court found this arrangement violated the rules requiring a qualified custodian to maintain control of retirement IRA assets.

    The consequences are severe. When home storage begins, the IRS treats the full fair market value of the IRA as a taxable distribution in that year—not just the bullion removed, but the entire balance. Federal and state income taxes become due, plus interest. If the IRA holder is under 59½, the 10% early distribution surcharge applies on top of ordinary income tax. Charges and interest continue to accrue until resolved.

    Any company marketing a “checkbook IRA” or “home storage IRA” for physical gold and silver is promoting an arrangement that the Tax Court has ruled illegal. Some companies continue to market these structures despite the McNulty decision. Do not attempt home storage of retirement-held bullion under any structure or legal argument, regardless of how it is presented.

    IRS-Approved Depositories: Where Your Gold Must Be Stored

    Physical bullion held in a self-directed Gold IRA must be stored at an IRS-approved depository. Major facilities include Delaware Depository (Wilmington, DE), Brinks Global Services (multiple locations nationwide), Texas Bullion Depository (Austin, TX), and International Depository Services (multiple locations). The custodian will have relationships with one or more approved facilities and will handle the logistics of transferring your holdings to storage upon purchase.

    When evaluating storage options, understand the difference between segregated and commingled storage. Segregated storage means your specific coins and bars are stored in a separate, labeled area—when you sell or take a distribution in kind, you receive those exact items. Commingled storage pools your bullion with other clients’ holdings of equivalent weight and purity; when you sell or take funds out, you receive equivalent units, not your specific original coins. Segregated storage is more expensive—typically $50–$100 more per year—but provides higher verifiability. Confirm the IRA includes online access so you can verify your holdings and track your specific gold at any time.

    Gold IRA vs. Gold ETF in a Regular IRA: The True 20-Year Cost

    Both a physical Gold IRA and a bullion ETF held in a conventional brokerage track the price of gold, and price appreciation is identical in both structures before fees. The meaningful difference is cost. Over a 20-year holding period, the fee gap between the two structures is substantial and compounds significantly.

    Gold IRA vs. Gold ETF: Cost Comparison on $100,000
    Factor Gold IRA (Physical) Gold ETF in Regular IRA
    Annual custodian + storage + insurance ~$500/year flat $0
    ETF annual expense ratio None 0.09% (IAU) to 0.25% (GLD)
    Initial dealer spread $3,000–$8,000 (3%–8%) $0
    Transaction fees $50–$100 per buy or sell $0 most brokerages
    Estimated 20-year total fee drag $15,000–$25,000 + spread $1,800–$5,000 (ETF ratio only)
    Counterparty risk None—physical metal ETF structure and custodian
    Liquidity Sell through dealer 1–5 days Instant market order

    For investors seeking price exposure without the complexity of physical storage, a bullion ETF in a regular brokerage achieves the same objective at significantly lower cost. Physical bullion has genuine advantages—no counterparty risk, a tangible asset that exists independently of any financial institution—but most retirees’ actual planning needs are met by the ETF at a fraction of the cost. The decision between the two should be made with full awareness of the fee gap over a realistic holding period.

    Which 401(k) Plans Allow Rollover to a Gold IRA?

    The ability to move your 401(k) funds into a self-directed Gold IRA depends on your employment status and plan rules. An active 401(k) at your current employer typically does not allow transfers while you remain employed—the plan assets must generally stay in the plan. Some plans do allow “in-service distributions” for participants over age 59½, which can then move to a self-directed IRA, but this is plan-specific and must be confirmed with your plan administrator directly.

    An old 401(k) from a former employer can typically be transferred without restriction. Once you have separated from that employer, the plan has no rule preventing you from moving the balance to a self-directed Gold IRA. A self-employed solo 401(k) offers the most flexibility: solo plans can often hold gold and silver directly within the plan structure or transfer to a Gold IRA with few complications. If you are self-employed, review whether holding bullion inside the solo 401(k) itself—rather than moving to a separate IRA—might achieve the same objective with simpler administration.

    Is a Gold IRA Rollover Right for You?

    Gold IRA Rollover Decision Guide
    Consider it if… Think twice if…
    You want physical bullion ownership with no counterparty risk—the gold exists independently of any financial institution Your primary goal is price exposure—a bullion ETF in a regular brokerage achieves that at 10%–20% of the annual cost
    You are moving funds from an old employer’s 401(k) where they are sitting idle and you want to diversify away from paper assets You are still employed at the plan’s sponsor—most active 401(k) plans do not allow transfers while employed, except in-service distributions after 59½
    Your balance is large enough that the fixed annual charge ($300–$600/year) represents a small percentage—on $200,000+, 0.25% annual drag is comparable to a gold ETF Your balance is under $50,000—at $25,000, a $500/year fee is 2.0% annually before the dealer spread, a significant drag on any investment
    You have confirmed both the custodian on the IRS approved list and an IRS-approved depository with segregated storage and online access Any company involved is marketing “home storage,” “checkbook IRA,” or numismatic coins as appropriate—these are red flags for prohibited transactions or inflated markups
    You plan to take in-kind distributions at retirement (receiving physical coins or bars rather than cash)—only a physical Gold IRA allows this You want simplicity and liquidity—selling physical bullion through a dealer takes 1–5 days; selling a bullion ETF takes seconds at market price

    Moving 401(k) funds to a self-directed Gold IRA is a legitimate strategy for the right investor, but it is not a default upgrade. Use a direct transfer exclusively—have the check sent to the new custodian, never to you personally. Confirm the specific custodian at IRS.gov, confirm the depository by name and facility address, and get every charge in writing before signing any agreement. For investors whose goal is portfolio insurance through physical bullion ownership and who have a balance large enough to absorb the annual cost structure, the self-directed IRA is a viable tool. For those seeking price exposure or comparing costs carefully, the ETF alternative deserves serious consideration first.

    Honest boundary: The Gold IRA industry includes reputable companies and deceptive ones. The FTC and SEC have both brought enforcement actions against gold and silver dealers. Verify any company’s claims independently and consider a fee-only financial advisor who does not receive commissions from bullion sales. This is not financial, legal, or tax advice.
  • 401(k) Early Withdrawal Penalty: 14 Exceptions and the 72(t) Rule

    401(k) Early Withdrawal Penalty: 14 Exceptions and the 72(t) Rule

    401(k) · Withdrawals · SECURE 2.0
    • The standard surcharge for taking money out before age 59½ is 10% plus ordinary income tax—in a 22% bracket that is a 32% combined hit before state taxes.
    • SECURE 2.0 added three new carve-outs effective 2024: terminal illness, domestic abuse survivor (up to $10,000), and emergency personal expense (up to $1,000 per year).
    • Rule 72(t) SEPP allows surcharge-free distributions at any age if you commit to a series of substantially equal periodic payments for 5 years or until 59½, whichever is longer.
    • 401(k) loans are not distributions—no tax, no surcharge if repaid within 5 years—but unpaid loans at job separation become taxable distributions.

    The Standard 401(k) Early Withdrawal Penalty: What It Actually Costs

    Withdrawing from a 401(k) before age 59½ triggers a 10% early withdrawal penalty on top of ordinary income tax on the full distributed amount. Unlike IRA distributions, which use a 10% voluntary withholding default, 401(k) distributions are subject to mandatory 20% federal withholding at the time of payment. This means you receive only 80 cents on the dollar immediately, and then owe the remaining taxes and the surcharge when you file your return. If the mandatory withholding isn’t enough to cover your total tax liability, you owe the difference.

    State income taxes apply on top of the federal burden in most states. Depending on your income bracket and location, the combined effective loss rate on taking money out early can reach 35% to 45% of the distributed amount. The practical result is that a $50,000 distribution may net you significantly less than $35,000 after all taxes and charges—and you have permanently reduced your tax-advantaged retirement savings, losing all future compounding on that amount.

    The following example illustrates the true cost for a worker in the 22% federal bracket residing in California, which imposes a 9.3% marginal rate at that income level.

    True Cost of a $50,000 Early 401(k) Withdrawal (Example)
    Cost Component Amount
    Federal income tax at 22% bracket $11,000
    Early withdrawal penalty 10% $5,000
    California state tax example 9.3% $4,650
    Total cost $20,650
    Amount you actually keep $29,350
    True Cost of a $50,000 Early Withdrawal True Cost of a $50,000 Early Withdrawal 22% federal bracket · example state tax of 5% $50,000 total withdrawn 10% penalty 22% fed. tax 5% state You keep $31,500 63% of what you withdrew 10% penalty: $5,000 Federal tax (22%): $11,000 State tax (~5%): $2,500 varies You actually receive: $31,500 State tax rate varies widely. California adds 9.3% at this bracket; some states have no income tax.

    All 14 Exceptions to the 10% Early Withdrawal Penalty

    Congress has layered in exemptions over decades of tax legislation. The original carve-outs were narrow; successive legislation including SECURE 2.0 in 2022 added three additional qualifying exceptions effective in 2024. Understanding which ones exist—and which your specific plan allows—is the first step before assuming a distribution will incur the surcharge.

    401(k) Early Withdrawal Penalty Exceptions
    Exception Who Qualifies Key Detail
    1. Age 55 separation Separated from that employer in year you turn 55+ Only from that employer’s plan, not old 401(k)s or IRAs
    2. Total and permanent disability Documented disability Must meet IRS definition
    3. Death Beneficiary receiving distributions No penalty on inherited distributions
    4. 72(t) SEPP Any age Must continue for 5 years or to age 59½, whichever longer
    5. Medical expenses Expenses exceeding 7.5% of AGI Only excess above threshold qualifies
    6. QDRO Alternate payee in divorce Must be a qualified domestic relations order
    7. IRS tax levy IRS issued levy against the plan Not a voluntary payment
    8. Military reservist Ordered to active duty 180+ days Must be called after September 11, 2001
    9. Corrective distributions Excess contributions returned Specific timing rules apply
    10. Health insurance premiums Unemployed workers After receiving unemployment 12+ weeks
    11. Terminal illness (SECURE 2.0 2024) Physician certifies terminal illness No dollar limit; can repay within 3 years
    12. Domestic abuse survivor (SECURE 2.0 2024) Self-certified victim Up to $10,000; can repay within 3 years
    13. Emergency personal expense (SECURE 2.0 2024) Any participant Up to $1,000 per year; one withdrawal per year allowed
    14. Federally declared disaster Affected individuals Up to $22,000; 3-year repayment window

    Rule 72(t): Penalty-Free Withdrawals at Any Age

    IRC Section 72(t) allows anyone—regardless of age—to take surcharge-free distributions from a retirement account by committing to a series of substantially equal periodic payments (SEPP). The IRS has approved three calculation methods: the required minimum distribution method (calculates the payment by dividing account balance by life expectancy each year, producing variable amounts), the fixed amortization method (calculates a fixed amount using life expectancy and a specified interest rate), and the fixed annuitization method (uses an annuity factor to calculate a fixed amount). The RMD method produces the lowest payments and is most conservative; the amortization and annuitization methods produce higher fixed sums.

    The payment series must continue for the longer of five years or until the account owner reaches age 59½. A 45-year-old beginning 72(t) distributions must continue them until age 59½—a 14.5-year commitment. A 57-year-old must continue them until at least age 62—five full years past the start date. During this entire period, the amount of each scheduled amount is largely locked in. You cannot increase, decrease, or pause the schedule without triggering the 10% surcharge retroactively.

    The one permitted modification is a one-time switch from the amortization or annuitization method to the RMD method, which allows participants to reduce amounts if their account value declines significantly. Other than that switch, changing the schedule for any reason—job change, financial hardship, account change—triggers the 10% hit on all prior distributions in the series, plus interest accrued since each one. This is not a program to begin without a complete financial plan in place.

    72(t) is a long-term commitment. Modifying the schedule before the period ends triggers the 10% surcharge retroactively on ALL prior distributions, plus interest. One missed payment or wrong calculation destroys the exemption. Do not attempt 72(t) without professional guidance.

    The Age-55 Rule: Early Access for Separated Workers

    If you separate from service—resign, are laid off, or retire—in the calendar year in which you turn 55 or older, you can access that specific employer’s 401(k) plan without the 10% early distribution surcharge. For qualified public safety employees (firefighters, police, emergency medical technicians), the threshold is reduced to age 50. The separation must be real; you cannot still be employed by the company and use this carve-out. Ordinary income tax still applies to every distribution—only the 10% extra cost is waived.

    The most important limitation of the age-55 rule is that it applies only to the plan of the employer you just separated from. It does not apply to 401(k) plans from previous employers that you left before turning 55, and it does not apply to IRA accounts of any kind. A common mistake is rolling an old 401(k) into an IRA and then assuming the age-55 carve-out still applies—it does not. Workers planning to use this exception should leave funds in the employer’s plan rather than rolling to an IRA until they have passed age 59½.

    401(k) Loans: Borrowing Without the Tax Hit

    A 401(k) loan is not a distribution. When you borrow from your 401(k), no income tax is due, no surcharge applies, and the money remains within your retirement account framework. The plan documents determine whether loans are permitted—not all plans allow them—but most large employer-sponsored plans do. The loan ceiling is the lesser of 50% of your vested account balance or $50,000. If your vested balance is $80,000, you can borrow up to $40,000. If your vested balance is $200,000, the maximum loan is still $50,000.

    Repayment must occur within five years in most cases, with level payments at least quarterly. The exception is loans used to purchase a primary residence, which may have extended repayment terms under some plan documents. You pay interest on the loan, but the interest goes back into your own account—effectively you pay interest to yourself. The hidden cost is the opportunity cost of lost investment returns on the borrowed amount during the loan period.

    The critical risk with 401(k) loans is job separation. If you leave the employer—voluntarily or not—with an outstanding loan balance, the loan typically becomes due by the tax filing deadline (including extensions) for the year of separation. If you cannot repay the full outstanding balance by that deadline, the unpaid amount is treated as a taxable distribution. For workers under 59½, the unpaid balance becomes a deemed distribution subject to both ordinary income tax and the 10% extra surcharge.

    If you lose your job and cannot repay the loan on time, the unpaid balance becomes a deemed distribution—fully taxable income plus the 10% surcharge if you are under 59½. The entire loan balance can become a tax bill overnight.

    Roth 401(k) Early Withdrawals: Different Rules

    Roth 401(k) accounts follow a different set of rules than traditional 401(k) accounts. Amounts deposited to a Roth 401(k) use after-tax dollars, which means they have already been taxed. Because of this, your original deposits—not your earnings—can be accessed at any time without income tax or surcharge, regardless of age. However, actual plan distributions from a Roth 401(k) are not neatly separated into original deposits and earnings; each distribution includes a proportional share of both.

    Earnings in a Roth 401(k) face the 10% extra cost if distributed before age 59½ and before the plan has satisfied a five-year aging requirement. Once you have both reached age 59½ and the plan has been open for at least five years, all Roth 401(k) distributions are completely tax-free and surcharge-free. The five-year clock begins on January 1 of the first year a Roth amount was deposited into that plan—not the year you made your first Roth account deposit elsewhere. Workers who start contributing to a Roth 401(k) late in their career should confirm the clock has been satisfied before taking distributions.

    The Three SECURE 2.0 Exceptions in Detail

    Terminal illness: A participant diagnosed with a terminal illness—defined as a condition that can reasonably be expected to result in death within 84 months—can take any amount from a 401(k) without the 10% surcharge. A physician must certify the condition in writing. Unlike many carve-outs, there is no dollar cap on the amount that can be accessed under this exception. The distribution is still subject to ordinary income tax. One notable feature: the participant can repay the amount to the plan (or to an IRA) within three years of the distribution date, and that repayment is treated as a rollover, eliminating the income tax on the original distribution through a refund process.

    Domestic abuse survivor: A participant who self-certifies that they have been a victim of domestic abuse by a spouse or domestic partner within the prior twelve months can access up to $10,000 (indexed for inflation) without the surcharge. Unlike the terminal illness carve-out, this one is self-certified—no third-party documentation is required at the time of the distribution, though the plan administrator may ask for a certification form. The amount remains taxable as ordinary income. Repayment within three years is permitted and reverses the income inclusion, again through a refund mechanism on the tax return.

    Emergency personal expense: Any plan participant can access up to $1,000 per calendar year for unforeseeable or immediate personal or family emergency expenses without the 10% surcharge. No documentation is required—the participant simply self-certifies the emergency need. Only one such distribution is allowed per plan per year. The plan cannot permit another emergency access in the following calendar year unless the participant has repaid the prior year’s amount or has made new deposits to the plan of at least the emergency distribution amount. This carve-out is the most accessible of the three SECURE 2.0 additions, as it requires no specific qualifying condition beyond a self-certified emergency.

    Action Checklist

    1. Confirm whether your situation qualifies for an exemption before taking funds out early — most people assume they owe the surcharge when they do not.
    2. Calculate the true cost including the 10% hit, your marginal tax rate, and state taxes — the total is almost always higher than expected.
    3. Explore a 401(k) loan first if the need is temporary — no tax, no surcharge, and you pay interest to yourself.
    4. If considering 72(t), hire a CPA or financial advisor to calculate the payment amount — one wrong number triggers retroactive charges on every prior distribution.
    5. If separating from employment at 55 or older, confirm the plan allows distributions under the age-55 carve-out before leaving — not all plans do.
    6. For SECURE 2.0 carve-outs (terminal illness, domestic abuse, emergency), gather documentation before requesting the distribution — the plan administrator will require it.
    7. Consult a CPA before any early access exceeding $10,000 — the tax modeling often reveals better alternatives.
    Honest boundary: The 14 exceptions listed here are based on federal law as of 2026. Individual plan documents may restrict which carve-outs apply to that specific plan. State charges may also apply on top of federal. This is not tax, financial, or legal advice.
  • 401(k) Contribution Limits 2026: Every Number You Need

    401(k) Contribution Limits 2026: Every Number You Need

    401(K) · SECURE 2.0 · 2026
    • Base employee deferral for 2026: $24,500 for all workers under age 50
    • Standard age-based top-up (ages 50–59 and 64+): $8,000, bringing the total to $32,500
    • SECURE 2.0 super catch-up (ages 60–63): $11,250, bringing the total to $35,750
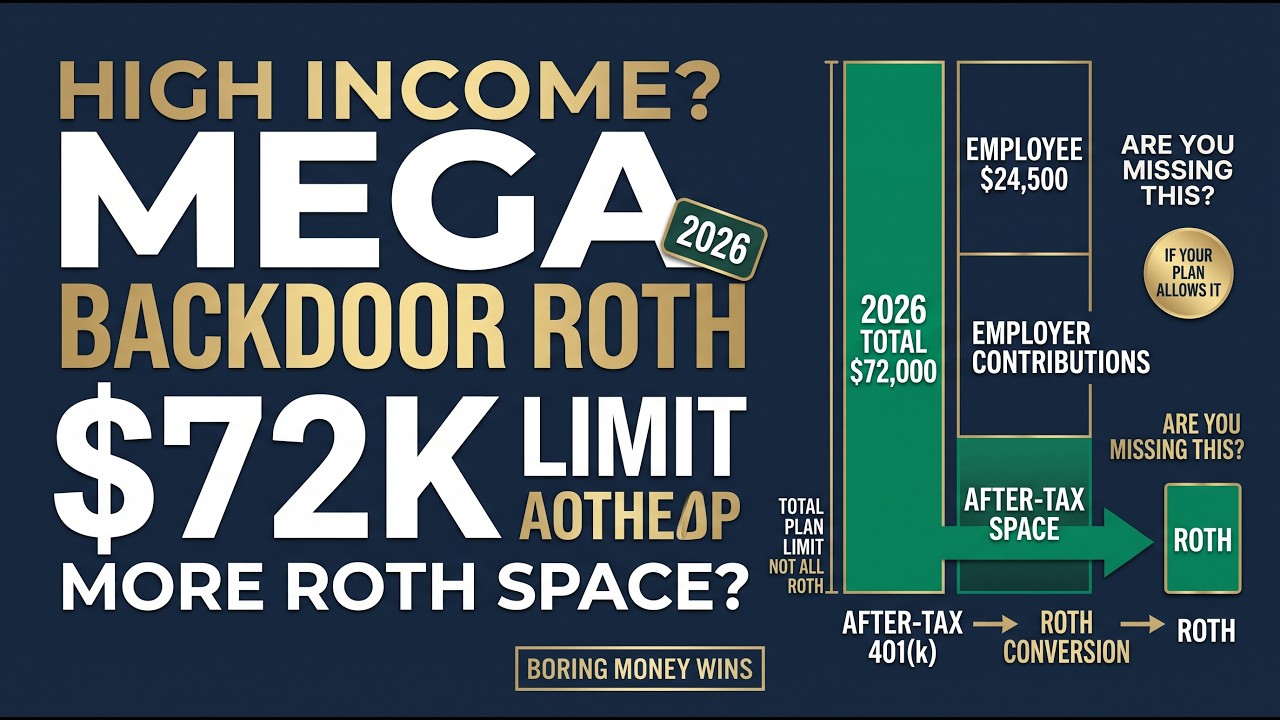
    • Overall limit including all employer additions: $72,000 per person per plan
    • Mandatory Roth designation applies to all supplemental deferrals if your 2025 income exceeded $145,000

    2026 Employee Contribution Limits: Base, Standard Catch-Up, and Super Catch-Up

    The IRS sets three distinct employee deferral tiers for 2026. Your age—specifically whether you turn 60, 61, 62, or 63 at any point during the year—determines which tier applies to you. Understanding which ceiling you fall under before the year begins lets you set your payroll election correctly from the first paycheck rather than scrambling to make up ground later.

    2026 401(k) Employee Contribution Limits
    Contribution Type Age Group 2026 Limit Notes
    Base deferral Under 50 $24,500 Pre-tax or Roth
    Standard catch-up 50–59 and 64+ $8,000 Roth-only if 2025 income over $145,000
    Super catch-up 60, 61, 62, 63 $11,250 SECURE 2.0 new in 2026
    Total max (ages 60–63) 60–63 $35,750 $24,500 + $11,250
    Overall limit all sources Any age $72,000 Includes employer contributions

    The Super Catch-Up Explained: Who Qualifies at Ages 60–63

    SECURE 2.0 Act Section 109 created a new category of age-based savings specifically for workers in a four-year window before the traditional supplemental deferral resumes. The super catch-up applies in any calendar year in which you turn age 60, 61, 62, or 63. If you turn 64 during the year, you lose access to the super catch-up and revert to the standard $8,000 ceiling—the window closes precisely at your 64th birthday year. This design reflects Congress’s intent to give workers a concentrated savings sprint in the final decade before typical retirement age.

    For 2026, workers born between January 1, 1963, and December 31, 1966, are eligible for the super catch-up. A worker born in 1963 turns 63 in 2026—still inside the window. A worker born in 1962 turns 64 in 2026 and drops back to the standard age-based top-up. Planning around this window is particularly important for workers on the boundary of the age cutoffs, because a single year’s difference in birth year can mean $3,250 less in allowable deferrals.

    The practical implication is significant: a 62-year-old who maximizes deferrals in 2026 can shelter $35,750 in a single year. Over the four-year window from ages 60–63, a consistently maximizing worker can put an additional $45,000 into a tax-advantaged account beyond the base deferral, assuming the super catch-up amount stays at $11,250. Workers in this age range should confirm their plan administrator has updated payroll systems to allow the higher ceiling, as some plans required system changes to accommodate SECURE 2.0.

    How the super catch-up is calculated: The amount equals the greater of $10,000 or 150% of the regular age-based top-up amount. In 2026 that produces $11,250 (150% × $7,500 regular top-up base). It adjusts with inflation going forward.

    Mandatory Roth Catch-Up for High Earners Over $145,000

    SECURE 2.0 also introduced a restriction on supplemental deferrals for high earners. If your FICA wages from a single employer exceeded $145,000 in 2025, all of your 2026 additional deferral amounts—whether the standard $8,000 or the super catch-up of $11,250—must be directed to a designated Roth account rather than a traditional pre-tax account. There is no option to split: the entire extra amount must be Roth. This applies only to the supplemental portion; the base $24,500 deferral can still be pre-tax if you choose.

    The immediate consequence for workers subject to this rule is that the extra amount provides no current-year tax deduction. The long-term consequence is that qualified withdrawals in retirement will be exempt from tax—a potential benefit depending on your projected bracket in retirement. However, if your plan does not offer a Roth feature, the law effectively disallows these additional deferrals entirely for high earners—your higher ceiling becomes $0 until the plan adds Roth functionality. The $145,000 threshold adjusts annually for inflation, so confirm the applicable figure for each tax year.

    Employer Contribution Limits: Match, Profit-Sharing, and the $72,000 Ceiling

    The $72,000 overall ceiling under IRC Section 415(c) covers the combined employee and employer amounts added to a single plan from a single employer in 2026. Employer additions—whether a match, profit-sharing, or other non-elective contributions—fill the gap between your employee deferral and the $72,000 cap. For most workers, the employer’s match alone does not come close to filling that space, leaving room for additional profit-sharing allocations if the plan is designed to provide them.

    2026 Overall 401(k) Limits Including Employer Contributions
    Scenario Combined Limit Notes
    Employee deferral max (base only) $24,500 No age-based top-up
    Employee + standard top-up (ages 50–59, 64+) $32,500
    Employee + super catch-up (ages 60–63) $35,750 Highest available employee ceiling
    Overall §415(c) limit (no age-based top-up) $72,000 Employee + employer combined
    Overall with standard top-up (ages 50–59, 64+) $80,000
    Overall with super catch-up (ages 60–63) $83,250 Maximum possible from all sources

    Employer additions—including match and profit-sharing—fill the space between an employee’s elected deferrals and the $72,000 Section 415(c) ceiling. The supplemental deferral amounts (standard or super) sit on top of the $72,000 for eligible workers, meaning they are not subject to the overall cap. A worker aged 60–63 can therefore receive up to $83,250 in total amounts from all sources combined in 2026.

    401(k) vs. IRA Limits: How They Interact

    401(k) and IRA annual caps operate completely independently of one another. Maxing out your 401(k) at $24,500 does not reduce your ability to add money to a traditional or Roth IRA. In 2026, the IRA ceiling is $7,500 ($8,600 if age 50 or older), and putting the maximum into both accounts is legal and beneficial for workers who can afford it. The two account types are governed by entirely separate sections of the tax code.

    The one practical constraint between the two involves Roth IRA income limits: Roth IRA contributions phase out for single filers between $161,000 and $176,000 of modified AGI, and for married filing jointly between $240,000 and $255,000 in 2026. The 401(k) has no income restriction on deferrals whatsoever—anyone with earned income can participate regardless of how much they earn. SIMPLE IRA caps are $16,500 in 2026, but that is a separate plan type with entirely different rules that does not interact with 401(k) ceilings.

    Multiple Employers: How the $24,500 Deferral Limit Works

    The $24,500 employee deferral cap is a per-person figure, not a per-plan figure. If you work two jobs simultaneously and both employers offer a 401(k), your combined employee deferrals across both plans cannot exceed $24,500. Neither employer is required to monitor your elections at the other employer; the responsibility to track and stay within the ceiling rests entirely with you. If you leave one job and join another during the year, the same rule applies—your total deferrals from all employers in the calendar year cannot exceed $24,500.

    Employer additions, however, are tracked separately per employer. Each employer can contribute up to its own $72,000 ceiling per plan. This means a worker with two employers could theoretically receive employer additions from two separate plans, each with its own $72,000 cap. Self-employed workers with a solo 401(k) can participate in two capacities: as the employee (up to $24,500 in deferrals) and as the employer (profit-sharing of up to 25% of net self-employment compensation), with the combined total capped at $72,000.

    What Happens If You Over-Contribute to Your 401(k)

    If you defer more than $24,500 across all 401(k) plans in 2026, you have made an excess deferral. The excess must be returned from the plan by April 15 of the following year (April 15, 2027, for 2026 excess). The plan will also distribute any earnings attributable to that excess amount. Both the over-deferred amount and the earnings are included in your taxable income in the year of the distribution.

    If you fail to pull back the excess by April 15, the situation worsens significantly. That amount is taxed twice: once in the year you deferred it (because it is included in income but not deductible) and again in the year you eventually withdraw it during retirement. This double-taxation outcome is entirely avoidable by monitoring your total deferrals throughout the year, particularly if you switch employers or work multiple jobs.

    Your responsibility, not the plan’s: Over-contributions across multiple 401(k) plans are the employee’s responsibility to catch and correct—not the plan administrator’s. If you change jobs mid-year, track your total deferrals yourself and notify the plan if you have exceeded the cap.

    Quick Reference: 2026 Limits at a Glance

    2026 401(k) Limits by Age Group — Quick Reference
    Age Group Employee Deferral Max with Employer Key Rule
    Under 50 $24,500 $72,000 Base only
    50–59 $32,500 $80,000 Standard top-up; Roth-only if 2025 wages > $145k
    60–63 $35,750 $83,250 Super catch-up under SECURE 2.0; Roth-only if 2025 wages > $145k
    64+ $32,500 $80,000 Returns to standard top-up; Roth-only if 2025 wages > $145k

    The numbers above reflect IRS guidance current as of October 2026. Contribution limits, income thresholds, and Roth designation rules can change each year with inflation adjustments or new legislation. This article is educational and does not constitute tax, legal, or investment advice. Consult a qualified tax professional or financial adviser before making elections that affect your retirement savings strategy.

  • Roth Conversions 2026: Brackets, IRMAA Cliffs, and the RMD-First Rule

    Roth Conversions 2026: Brackets, IRMAA Cliffs, and the RMD-First Rule

    401(k) · ROTH · TAX STRATEGY
    • You must take your full required minimum distribution before doing any Roth conversion in 2026—RMDs cannot be converted, only amounts above that minimum can be.
    • The 22% federal bracket tops out at $103,350 single/$206,700 married—shifting funds up to that ceiling is the sweet spot for most retirees.
    • IRMAA looks back 2 years: a large 2026 transfer to the sheltered side can raise 2028 Medicare premiums by $74–$407 per month per person.
    • There is no income limit on these status switches—only on direct Roth IRA contributions. Anyone can convert regardless of income.

    The RMD-First Rule: You Cannot Convert Your RMD

    The IRS requires that any Required Minimum Distribution be taken before any pre-tax-to-Roth transfer can occur in the same year. This is not optional and not a planning choice—it is a sequential legal requirement. These mandatory amounts cannot be rolled over to another IRA and cannot be moved to the sheltered side; they must be distributed as ordinary taxable income and cannot be recaptured. Only amounts above the minimum are eligible for the switch. For a retiree with a $1.2 million IRA at age 76, the required payout might be $53,000—that entire amount must come out first before a single additional dollar can go into a pre-tax-to-Roth conversion.

    The mandatory-first rule creates a particular trap in the first year these distributions are required, which is currently age 73 under the SECURE 2.0 Act. The IRS allows a one-time deferral of the first-year required amount to April 1 of the following year. This deferral option looks appealing—delay income, delay the levy—but it creates a double-stack problem: if you defer your age-73 payout to April 1 of the year you turn 74, you must also take your age-74 amount by December 31 of that same year. Two full distributions hit your taxable return in a single calendar year, potentially pushing you into a higher bracket and triggering Medicare surcharges that would not have occurred with ordinary annual distributions.

    “In your first required-distribution year, deferring to April 1 looks appealing but means two mandatory payouts hit your return in the same calendar year. Most advisors recommend taking the first payout in the year you turn 73 to avoid the double stack.”

    2026 Federal Tax Brackets: Where to Stop Your Roth Conversion

    The right stopping point for a pre-tax-to-Roth shift depends on your current bracket, your projected future receipts from Social Security and mandatory distributions, and what you expect tax rates to look like in years ahead. The One Big Beautiful Bill Act (OBBBA), signed July 4, 2025, made the 2017 Tax Cuts and Jobs Act rates permanent—the scheduled 2026 sunset did not happen. The rate-increase argument that drove aggressive 2024–2025 transfer strategies no longer applies. These switches still make sense for many retirees in 2026, but the driver is now personal bracket management—specifically avoiding the mandatory-payout-plus-benefit stack that hits at 73—not a race against expiring rates.

    2026 Federal Income Tax Brackets
    Rate Single Filer Married Filing Jointly
    10% Up to $11,925 Up to $23,850
    12% $11,926–$48,475 $23,851–$96,950
    22% $48,476–$103,350 $96,951–$206,700
    24% $103,351–$197,300 $206,701–$394,600
    32% $197,301–$250,525 $394,601–$501,050
    35% $250,526–$626,350 $501,051–$751,600
    37% Above $626,350 Above $751,600

    Most retirees target shifting funds up to the top of the 22% or 24% bracket. Moving into 32%+ usually only makes sense if you expect significantly higher future rates or want to reduce estate exposure.

    The Tax Stack Problem: How Social Security and RMDs Push Into Higher Brackets at Age 73 The Tax Stack Problem: Income Collision at Age 73 Married filing jointly. Illustrative figures based on 2026 brackets. Annual Taxable Income $0 $50k $100k $150k $200k $250k 12% top 22% top 32%+ Other income ~$55,000 Ages 62–65 12% bracket Low income gap years Social Security ~$30k Other income ~$55,000 Ages 66–72 22% bracket SS begins to stack Required payouts ~$53k+ (taxable, grows) SS 85% taxable ~$26k Other income ~$55,000 ~$134k total Age 73+ 32%+ bracket risk Benefits + payouts collision Pension / interest / other income Social Security (85% taxable above threshold) Mandatory payouts (taxable, grows annually) Illustrative married filing jointly scenario. 2026 federal brackets. RMD based on $1.2M IRA at 76, IRS Uniform Lifetime Table.

    IRMAA Cliffs: How a Roth Conversion Can Raise Your Medicare Bill

    Medicare’s income-related surcharge uses Modified Adjusted Gross Income from two years prior to determine your premium tier. A pre-tax-to-Roth shift in 2026 will affect your 2028 Medicare bills—and the effect is not graduated. The IRMAA system uses hard thresholds: crossing from one tier to the next by a single dollar triggers the full surcharge for that tier, not a proportional amount. This cliff structure means that a transfer of $5,000 beyond a threshold can cost several thousand dollars in extra premiums over the following year—wiping out much or all of the status benefit for that portion of dollars.

    For a married couple, the IRMAA thresholds are exactly double the single thresholds, which makes the math symmetrical but the stakes twice as high on a per-household basis. The two-year lookback also means the damage from a carelessly large transfer is not visible until Medicare bills arrive two years later. By then, the income year cannot be undone, and there is no retroactive correction available except filing a Life-Changing Event (LCE) appeal if income changed due to a qualifying event like retirement or death of a spouse.

    2026 IRMAA Thresholds and Medicare Part B Surcharge
    Individual MAGI Married Filing Jointly Monthly Part B Surcharge
    Up to $103,000 Up to $206,000 $0 (base rate $185)
    $103,001–$129,000 $206,001–$258,000 +$74.00
    $129,001–$161,000 $258,001–$322,000 +$185.00
    $161,001–$193,000 $322,001–$386,000 +$295.90
    Above $193,000 Above $386,000 +$406.90
    Warning: One dollar over an IRMAA threshold triggers the entire tier—up to $407/month per person in extra Medicare premiums. Stop your pre-tax-to-Roth transfer $1,000–$2,000 below each threshold to leave a buffer.

    The Five-Year Rule for Roth Conversions

    Each pre-tax-to-Roth transfer creates its own five-year holding period for penalty-free access to the earnings on that shifted amount. The clock starts on January 1 of the year in which the transfer is made—so a switch done in October 2026 starts its five-year clock on January 1, 2026 and matures on January 1, 2031. This matters primarily for retirees under age 59½ who might need to access those funds; earnings accessed before the five-year clock expires are subject to a 10% early withdrawal penalty, even if the account is a Roth IRA. Importantly, the basis itself—the contributed amount you originally moved—is always accessible without penalty at any time, because that levy was already paid.

    After age 59½, the five-year rule changes significantly. Once you are past 59½ and at least one Roth IRA has been open for five or more years, all Roth IRA earnings become accessible levy- and penalty-free, regardless of when individual transfers occurred. This means retirees who opened any Roth IRA at least five years ago—even with a small original contribution—have effectively cleared the five-year hurdle for all future switches once they pass 59½. For most people planning these moves in their 60s and 70s, the five-year rule is largely a bookkeeping concern rather than a practical barrier.

    State Taxes on Roth Conversions

    Pre-tax-to-Roth transfers are treated as ordinary income by most states, meaning they sit on top of your federal return and are levied at your state’s marginal rate in the year of the switch. States with high rates—California (up to 13.3%), New York (up to 10.9%), New Jersey (up to 10.75%), and others—add a substantial layer on top of federal rates that can change the math entirely. A transfer that looks efficient at a blended 22% federal rate becomes significantly less attractive when state levies push the effective rate above 30%.

    Some states treat retirement income differently. Illinois, Pennsylvania, and Mississippi exclude most or all retirement income from state levy, which effectively lowers the cost of these moves in those states. Several states have no income tax at all—Texas, Florida, Nevada, Wyoming, Washington, South Dakota, and Alaska—making this purely a federal calculation there. If you are considering a geographic move in retirement, the interaction between state income levies and this status-switch strategy is worth modeling explicitly before relocating: a move from California to Nevada before a large series of switches can be worth hundreds of thousands of dollars over a retirement.

    The Pro-Rata Rule: The Trap for Backdoor Roth Conversions

    The pro-rata rule is the IRS mechanism that prevents taxpayers from selectively moving after-tax IRA basis while leaving pre-tax IRA money in place. If you have any pre-tax money in any traditional IRA—including SEP-IRAs, SIMPLE IRAs, and rollover IRAs from old 401(k)s—the IRS treats all IRA balances as a single pool when calculating the taxable portion of any switch. You cannot choose which dollars to move; the ratio of pre-tax to after-tax money applies to every transfer proportionally. A retiree with $900,000 in pre-tax IRA money and $100,000 in after-tax contributions cannot shift just the $100,000 in basis tax-free—90% of every move will be taxable regardless of intent.

    The pro-rata rule does not apply to 401(k) in-plan transfers or to the mega backdoor strategy executed inside a 401(k) that allows after-tax contributions. The cleanest solution for retirees caught by the pro-rata rule is to roll pre-tax IRA balances into a current employer’s 401(k) if the account accepts rollovers—this removes the pre-tax IRA money from the pro-rata calculation entirely and allows after-tax IRA basis to be moved without further levy. Not all 401(k) plans accept incoming rollovers, so this requires confirming terms before attempting the strategy.

    When Roth Conversions Don’t Make Sense

    The case for switching weakens or disappears in several specific situations. If you are already in the 32% bracket or above and expect your burden to be substantially lower in future years—because your Social Security will be modest, your mandatory distributions will be small due to a smaller account balance, or you expect to move to a low-tax state—you may be moving funds at a higher rate than you will eventually pay on normal distributions. Similarly, if you need to access the shifted funds within five years and are under age 59½, the earnings remain subject to the 10% early withdrawal penalty, reducing the benefit of the strategy.

    Crossing an IRMAA threshold without a sufficient long-term offset is another scenario where these moves do more harm than good. If a $5,000 transfer beyond a threshold triggers $888 in additional Medicare premiums per year (a married couple each paying $74/month in the first IRMAA tier), the break-even on that marginal move may not occur for decades. Finally, if your heirs have high incomes and will pay the same or similar rates on an inherited traditional IRA as you would pay on a pre-tax-to-Roth switch now, the move provides no benefit to the overall family estate—it only accelerates the payment without reducing the total amount owed.

    Action Checklist

    1. Take your full required minimum distribution before starting any pre-tax-to-Roth transfer — confirm the amount with your benefits administrator each January.
    2. Calculate your current taxable income and find the ceiling of your target bracket — that is your maximum eligible amount for the switch.
    3. Check IRMAA thresholds for 2 years out — if moving funds in 2026, check 2028 premium tiers and stay $1,000–$2,000 below the next level.
    4. Draw from oldest pre-tax IRAs or 401(k) first — this reduces accounts that will generate mandatory distributions at 73.
    5. Pay the resulting levy from a taxable brokerage account, not from the IRA — using IRA funds reduces the shifted amount and the compounding benefit.
    6. Document each move on Form 8606 and keep records of each year’s transfer amount and levy paid.
    7. Review the transfer amount annually — the right figure changes as markets move, income changes, and thresholds adjust for inflation.
    Honest boundary: The math here is sensitive to future rates, which no one knows. The case for switching pre-tax funds is strongest when current rates are relatively low and future income (benefits plus mandatory distributions) is expected to be high. Confirm the numbers with a CPA or fee-only advisor before large moves. This is not financial or legal advice.
  • Spend Down Your 401(k) Before Social Security: The Tax Case

    Spend Down Your 401(k) Before Social Security: The Tax Case

    401(k) · TAX STRATEGY · 2026
    • Gap years between retirement and Social Security (ages 62–70) are the ideal window to draw pre-tax 401(k) at your lowest marginal bracket.
    • Every dollar withdrawn now at 22% may have been withdrawn at 37%+ later when benefits plus mandatory distributions stack on top of each other.
    • IRMAA Medicare surcharges hit at $103,000 single/$206,000 married—drawing from your 401(k) early can keep future earnings below those cliffs.
    • Roth conversions in gap years use the same low-bracket window to permanently reduce future mandatory withdrawal obligations.

    The Gap-Year Window: Why Ages 62–70 Are Your Best Tax Opportunity

    Once Social Security benefits begin, up to 85% of those payments become taxable and stack directly on top of everything else you receive. Once Required Minimum Distributions kick in at age 73, those mandatory withdrawals add another layer that grows larger each year as the IRS divisor shrinks. The result is a compounding pile that many retirees never anticipated when they were still working. The gap years—the period after leaving work but before benefits and mandatory distributions begin—are often the lowest-tax years of an entire retirement, and they are frequently wasted.

    During this window, a retiree might have amounts near zero or confined to interest and dividends. That creates room in the 12% and 22% federal brackets that will never be available again once benefits and mandatory payouts arrive. Voluntarily drawing from a traditional 401(k) or IRA during the gap years—or converting those pre-tax dollars to Roth—fills that low-rate space intentionally. Every dollar pulled at 22% today is a dollar that will not be pulled at 32% or 37% later when the taxable pile grows taller.

    The math is straightforward even if the psychology is not. Retirees who worked hard to accumulate tax-deferred savings often resist drawing on them early. But the tax deferral was never meant to last forever—the IRS will collect eventually, and the only question is at what rate. Taking deliberate control of the timing is not spending down a nest egg recklessly; it is managing a tax bill strategically. The gap-year window is the last opportunity most retirees will have to do this at favorable rates.

    How Social Security and RMDs Create a Tax Collision at Age 73

    The “tax torpedo” is not a metaphor—it describes a real mathematical event that happens when Social Security benefits and Required Minimum Distributions arrive in the same years. Those benefits are unique among retirement income sources: receiving them causes up to 85% of the amount to become taxable, and the threshold at which that taxation kicks in has not been adjusted for inflation since 1993. A couple receiving $50,000 in combined benefits and $40,000 in mandatory distributions is not a wealthy couple by most definitions, but their effective tax burden can rival that of a working professional earning $150,000.

    Mandatory distributions are fixed by law and grow each year. The IRS Uniform Lifetime Table divides your account balance by a factor that shrinks annually, which means even if the market is flat your required withdrawal increases as you age. An $800,000 401(k) at age 73 requires a withdrawal of roughly $30,000. The same account at age 80, even without growth, requires a larger percentage. If the market has grown, the dollar amount of the annual minimum grows with it. There is no ceiling, no opt-out, and no averaging available to soften the blow in any given year.

    When these two sources collide—benefits that trigger taxation of payments, and mandatory withdrawals that keep rising—a retiree with otherwise moderate spending can find themselves pushed into brackets they never saw while working. The effective marginal rate in this zone can exceed the stated bracket rate because each additional dollar causes more of the benefit to become taxable, compounding the rate. Advisors sometimes call this the “torpedo zone” because retirees sail into it without warning.

    The Tax Stack at Age 75 (Example)
    Income Source Gross Amount Taxable Amount
    Social Security $28,000 $23,800 (85%)
    RMD from 401(k) $45,000 $45,000 (100%)
    Interest and dividends $8,000 $8,000
    Total AGI — $76,800
    Federal bracket — 22% on income above $47,150

    This same retiree, drawing from the 401(k) during the gap years from 62 to 70, could have reduced the 401(k) balance and the resulting RMD by $15,000–$20,000 annually.

    IRMAA: The Medicare Surcharge That Punishes High 401(k) Balances

    IRMAA—the Income-Related Monthly Adjustment Amount—is a surcharge added to Medicare Part B and Part D premiums for retirees whose earnings exceed certain thresholds. The surcharges are not trivial: they range from roughly $70 to more than $400 per month per person, and a married couple in the highest tier can pay an additional $10,000 per year in Medicare premiums above the base rate. These costs compound across years of retirement and are entirely invisible to retirees who focus only on their 401(k) balance rather than their projected taxable total.

    The critical feature of IRMAA is its two-year lookback. Medicare uses your Modified Adjusted Gross Income from two years prior to determine your current year’s premium tier. This means 2026 Medicare premiums are based on 2024 figures. A large mandatory distribution taken in 2024—or a large Roth conversion—will raise Medicare costs in 2026 with no ability to retroactively undo the impact. Retirees who plan ahead can manage their totals in anticipation of IRMAA thresholds; those who do not discover the surcharge only after the Medicare bill arrives.

    2026 IRMAA Thresholds — Medicare Part B Monthly Premium
    Individual MAGI Married Filing Jointly MAGI Monthly Part B Premium
    Up to $103,000 Up to $206,000 $185.00 (base)
    $103,001–$129,000 $206,001–$258,000 $259.00
    $129,001–$161,000 $258,001–$322,000 $370.00
    $161,001–$193,000 $322,001–$386,000 $480.90
    Above $193,000 Above $386,000 $591.90

    The Roth Conversion Strategy During the Gap Years

    Roth conversions during the gap years use the same low-bracket window to accomplish something more permanent: eliminating future mandatory withdrawal obligations on those dollars entirely. When you convert a traditional 401(k) or IRA to a Roth IRA, you pay ordinary taxes on the converted amount in the year of the switch. Those funds then grow tax-free, and unlike traditional accounts, Roth IRAs have no Required Minimum Distributions during the owner’s lifetime. Each dollar converted is a dollar removed from the forced-distribution calculation at age 73.

    The arithmetic of conversion only favors the retiree when current rates are lower than future rates. For many retirees, the gap years provide exactly that condition. A couple with no wage earnings, modest interest, and a Social Security start date still in the future may have room in the 12% or 22% bracket for substantial conversions. Converting $50,000 per year for eight gap years—at an average blended rate of 18%—removes $400,000 from the mandatory-distribution base while paying less in taxes than those same dollars would incur as required payouts at 32% a decade later.

    The converted funds also benefit from tax-free compounding. A dollar converted at 62 and invested in a Roth IRA has more than a decade to grow before the original owner reaches 73, and all of that growth is permanently sheltered from ordinary taxes. For heirs, the advantage continues: inherited Roth IRAs avoid the taxation that traditional inherited IRAs impose, though the 10-year distribution rule now applies to most non-spouse beneficiaries under the SECURE 2.0 Act.

    “The math only works if you pay conversion taxes from a taxable account—not from the IRA itself. Using IRA funds to pay taxes reduces the compounding benefit of the conversion.”

    When Spending Down the 401(k) First Does Not Make Sense

    The gap-year drawdown strategy is compelling in the right circumstances, but it is not universally correct. If your projected retirement earnings—from pensions, rental receipts, Social Security at an early filing date, or part-time work—means you will remain in a high bracket throughout retirement, the gap may not actually be a low-rate window. Similarly, if you expect tax law to change substantially in your favor, or if your benefit check is small enough that the 85% inclusion rule creates little additional tax burden, the urgency to pre-draw the 401(k) diminishes.

    Heirs can sometimes benefit more from inheriting pre-tax assets than Roth assets, particularly if your heirs are in lower tax brackets than you. The 10-year distribution window for inherited IRAs under current law means a beneficiary in the 12% bracket draws down an inherited traditional IRA with minimal tax cost—potentially less than you would have paid converting at 22% during your lifetime. If you have large medical deductions, significant charitable giving, or substantial losses that already reduce your taxable total, those offsets may make the case for conversion weaker than the simple bracket math suggests. State taxes add another layer: if you live in a state with no state levy, the conversion cost is lower in absolute terms, but if you live in California or New York, you are paying 8–13% on top of federal rates for every dollar converted.

    Your Gap-Year Playbook

    Step 1: Calculate Your Window

    Start by estimating your Social Security benefit at ages 62, 67, and 70 using SSA.gov’s online calculator — the payment gap between filing dates is often $800–$1,500 per month, which shapes every other decision. Then project your future mandatory distributions using the IRS Uniform Lifetime Table applied to your current 401(k) balance with a realistic growth assumption. The difference between your current retirement earnings and what you will receive once benefits plus mandatory payouts arrive tells you how wide the gap-year window is and how aggressively to use it.

    Step 2: Fill the Bracket

    Identify your lowest available federal bracket during the gap years — for most retirees with no wage earnings, there is meaningful room in the 12% and 22% brackets before benefits begin. Coordinate distributions and Roth conversions to fill up to the top of the 22% bracket without crossing into 24%. Household totals determine bracket and IRMAA exposure, not individual figures alone, so model your spouse’s earnings and benefit timing together. The IRMAA two-year lookback means planning distributions in year N requires awareness of what Medicare will cost in year N+2.

    Step 3: Model the RMD Impact

    Every dollar of pre-tax 401(k) balance you convert to Roth during the gap years is a dollar removed from your future mandatory-distribution calculation at age 73. Work with a fee-only financial advisor or CPA to run the multi-year projection with your actual numbers — the optimal amount to convert each year depends on balance size, benefit payment amounts, expected investment returns, and life expectancy assumptions that differ for every household. The modeling work is not optional: the strategy requires a full scenario comparison to quantify whether the conversion tax cost today is less than the forced-distribution tax cost later.

    Honest boundary: The optimal withdrawal sequence depends on your specific balances, income sources, tax rates, and longevity assumptions. The general case for spending down pre-tax accounts before Social Security is strong for many high earners, but it is not universal. This is not tax or financial advice.
  • Roth 401(k) RMDs Eliminated: What SECURE 2.0 Changed

    Roth 401(k) RMDs Eliminated: What SECURE 2.0 Changed

    401(k) · SECURE 2.0 · 2024
    • Beginning January 1, 2024, designated Roth accounts in 401(k), 403(b), and governmental 457(b) plans are exempt from required minimum distributions during the original owner’s lifetime.
    • Before 2024, designated Roth 401(k) owners faced mandatory payouts just like traditional 401(k) owners—the most common reason advisors told clients to roll to a sheltered IRA before age 73.
    • This change removes the main argument for rolling designated Roth 401(k) balances to the IRA near retirement.
    • Beneficiaries still face distribution requirements after the owner’s death—the lifetime exemption covers the original owner only.

    What Changed and When: The SECURE 2.0 Elimination of Roth 401(k) RMDs

    Before SECURE 2.0, designated Roth accounts inside employer plans—401(k), 403(b), and governmental 457(b)—were subject to the same required minimum distribution rules as their pre-tax counterparts. Starting at age 73, owners were required to take annual distributions calculated by dividing the prior year-end account balance by an IRS life expectancy factor. This created a mismatch: Roth IRA owners faced no lifetime mandatory payouts, but designated account holders in employer plans did. The common workaround was to roll the account into the sheltered IRA before these annual minimums began—triggering the same result, but requiring action and sometimes sacrificing plan-specific protections in the process.

    SECURE 2.0, enacted December 29, 2022, eliminated this disparity effective January 1, 2024. Designated Roth accounts in employer plans now follow the same no-payout rule as the Roth IRA for the original account owner. Owners can let these balances compound indefinitely during their lifetime without being forced to take distributions. The change applies to all designated account balances regardless of when the contributions were made—there is no transitional period or grandfathered balance rule.

    Roth Account RMD Rules: Before and After SECURE 2.0
    Account Type Before 2024 From 2024 Forward
    Roth IRA No mandatory payouts during owner’s lifetime No mandatory payouts — unchanged
    Designated Roth 401(k) Annual distributions required starting at age 73 No mandatory payouts during owner’s lifetime
    Designated Roth 403(b) Annual distributions required starting at age 73 No mandatory payouts during owner’s lifetime
    Designated Roth 457(b) (governmental) Annual distributions required starting at age 73 No mandatory payouts during owner’s lifetime
    Traditional 401(k) Annual distributions required starting at age 73 Still required starting at age 73 — no change
    Traditional 401k vs Roth 401k: RMD Impact Comparison Two Paths in Retirement: RMDs vs. No RMDs What happens to your account balance starting at age 73 Traditional 401(k) Balance at 73 $800,000 Age 73 RMD −$29,200 Age 74 RMD −$31,400 (grows each yr) Age 75, 76, 77… Larger & larger forced payouts Tax Bill Every Year Heirs pay income tax on inherited balance Roth 401(k) Balance at 73 $800,000 Age 73, 74, 75… Still invested No payouts — Ever Compounds untouched Balance grows tax-free every year you live Tax-Free to Heirs No lifetime payouts Heirs inherit income-tax-free SECURE 2.0 Act, effective January 1, 2024. RMD amounts illustrative based on IRS Uniform Lifetime Table.

    Stay in the Plan vs. Roll to Roth IRA: Does the Change Affect Your Decision?

    For years, the standard pre-retirement advice for designated Roth 401(k) owners was to roll over to the IRA before turning 73. The primary reason: avoid lifetime mandatory payouts on the 401(k) balance. That reason no longer exists. But other differences between staying in the plan and rolling over remain real, and the right answer depends on your specific situation—investment options, fee structure, creditor exposure, and the five-year clock discussed below.

    Roth 401(k) vs. Roth IRA: Staying in Plan vs. Rolling Over (Post-2024)
    Factor Stay in Plan Roll to Tax-Free IRA
    Lifetime mandatory payouts None (post-2024) None
    Investment options Limited to plan investment menu Unlimited—any brokerage, ETF, or fund
    Annual fees Often lower institutional share class fees Varies by brokerage; some are fee-free
    Creditor protection ERISA federal protection—strong and broad State law varies widely; often weaker
    Age-55 early access Penalty-free at 55 if separated from employer No age-55 exception; 59½ rule applies
    Five-year rule Plan’s existing designated-account clock continues IRA clock governs; may restart if IRA is newer than 401(k)

    Creditor protection deserves special attention for certain professionals. ERISA-qualified plans—including 401(k) and 403(b)—carry federal creditor protection that is essentially unlimited. A judgment creditor generally cannot reach funds inside an ERISA plan. Tax-free IRA creditor protection, by contrast, is governed by state law and varies dramatically: some states offer strong protection, others limit it to amounts necessary for support, and a few offer none at all for non-bankruptcy situations. Physicians, attorneys, engineers, and others with litigation exposure may have a concrete reason to keep substantial balances inside the ERISA-protected employer plan even when other factors favor rollover.

    The Five-Year Clock Problem at Rollover

    When you roll a designated Roth 401(k) into the sheltered IRA, the earnings inside the account become subject to the IRA’s five-year rule—not the plan’s five-year rule. For earnings to come out exempt, the IRA must have been open for at least five years (measured from January 1 of the first contribution year), and the owner must be at least 59½. If the receiving IRA was opened after your designated 401(k), rolling over may push your earnings access date later than if you had stayed in the employer plan.

    This matters most for people who have been contributing to a designated Roth 401(k) for years but never opened the separate IRA. A participant who has had a designated account since 2018 but opens the IRA for the first time in 2026 to receive a rollover will not have exempt earnings access until 2031—five years from the IRA opening—regardless of how long the money sat in the 401(k). The employer plan’s clock does not transfer.

    The designated 401(k) five-year clock does not transfer to the IRA clock. If the receiving IRA is newer than your designated account, rolling over may reset the waiting period for exempt earnings access.

    The practical fix is simple: open the sheltered IRA now, even if you fund it with only $1. The five-year clock starts on January 1 of the year for which you make your first contribution. An account opened and funded in 2024 has a clock that began January 1, 2024. If you roll your designated 401(k) balance into that IRA in 2028, the earnings clock is already four years old—only one year from the five-year threshold. Starting the clock early costs almost nothing and can save years of waiting.

    Beneficiary Rules After the Owner’s Death

    The SECURE 2.0 mandatory-payout elimination is a lifetime benefit for the original account owner only. After the owner’s death, the SECURE Act of 2019 rules govern how beneficiaries must distribute inherited designated Roth 401(k) balances. Unlike the pre-2024 era when inheriting such an account was functionally identical to inheriting any other defined contribution plan for distribution purposes, beneficiaries of inherited designated accounts must still comply with these requirements—even though those distributions will generally be exempt from ordinary income levy.

    Inherited Designated Roth Account: Distribution Rules for Beneficiaries
    Beneficiary Type Distribution Rule Tax Treatment
    Surviving spouse Can roll to their own account; no lifetime mandatory payouts as owner Tax-free if five-year rule met
    Minor child of owner 10-year rule begins when child reaches majority (age 21 in most states) Tax-free if five-year rule met
    Disabled or chronically ill Life expectancy stretch payments allowed Tax-free if five-year rule met
    All other beneficiaries (adult children, siblings, etc.) Must empty account within 10 years of owner’s death Tax-free if five-year rule met

    Distributions from an inherited designated account are exempt from income levy when the five-year rule has been satisfied—meaning the original owner opened the account at least five years before the distributions occur. For most long-standing designated 401(k) accounts, this condition will already be met by the time of inheritance. However, the 10-year rule still forces liquidation within a decade of the owner’s death, which limits the compounding runway for non-spouse adult beneficiaries.

    Estate Planning With the Roth 401(k): The New Opportunity

    The elimination of lifetime mandatory distributions from designated accounts in employer plans creates a meaningful estate planning opportunity that did not exist before 2024. Without forced annual payouts, the balance can compound untouched for decades while the owner draws down pre-tax accounts, Social Security, or other taxable income sources. Every dollar that remains inside the account continues growing free of ordinary levies—and can pass to heirs without triggering an income event, subject only to the 10-year distribution rule for non-spouse beneficiaries.

    Consider a 65-year-old retiree with $300,000 in a designated Roth 401(k) and $800,000 in a traditional 401(k). Before SECURE 2.0, they faced annual distributions from both accounts at age 73. Now, they can draw from the traditional 401(k) first—managing income through sheltered conversions, qualified charitable distributions, or simply spending down pre-tax funds—while the designated account compounds entirely undisturbed. Over 20 years at a 7% annualized return, that $300,000 balance could grow to roughly $1.16 million, all of which passes to heirs income-levy-free.

    For married couples, the opportunity extends across two lifetimes. When the first spouse dies, the surviving spouse can roll the inherited designated balance into their own sheltered IRA—treating it as their own account, not an inherited one. This means no lifetime mandatory distributions for the surviving spouse either. The balance continues compounding through the second spouse’s life and passes to children or other beneficiaries subject only to the 10-year post-death distribution rule. Two generations of sheltered compounding, and the government collects ordinary levies on none of it.

    Action Checklist

    1. Confirm your plan recognizes the 2024 rule change — contact your benefits administrator to verify that designated Roth account balances are no longer subject to mandatory distribution calculations starting with the 2024 plan year.
    2. Cancel any automatic distribution elections you set on a designated Roth balance — if your 401(k) was sending annual payouts from that sub-account, stop that election immediately to preserve the compounding benefit.
    3. Reconsider the rollover strategy — if your only reason for planning a rollover was to escape mandatory payouts, that reason is gone. Evaluate investment options, creditor protection, plan fees, and the five-year clock implications before deciding.
    4. Open a sheltered IRA now if you do not have one — even a contribution of $1 starts the five-year clock in case you roll over later, and prevents a clock reset from delaying exempt earnings access.
    5. Update beneficiary designations on your designated account — ensure your estate plan reflects the 10-year post-death distribution rule for non-spouse beneficiaries and confirm your surviving spouse is named if you want the rollover option available to them.
    6. Review your withdrawal sequence with an advisor — designated Roth 401(k) balances can now serve as long-term compounding vehicles or estate planning tools without forced-payout pressure, which may change the optimal order in which you spend down different account types.
    Honest boundary: The SECURE 2.0 mandatory-payout elimination for designated Roth accounts is law. But plan administrators implement it at their discretion, IRS guidance on edge cases continues to evolve, and beneficiary rules are complex. Verify with your benefits administrator and a qualified advisor. This is not tax, financial, or estate planning advice.
  • Mega Backdoor Roth 2026: How to Put $47,500 Into Roth

    Mega Backdoor Roth 2026: How to Put $47,500 Into Roth

    401(k) · SECURE 2.0 · 2026
    • The 2026 total 401(k) limit is $72,000, covering employee deferrals, employer match, and voluntary after-tax contributions combined.
    • The mega backdoor Roth fills the gap between your regular contributions plus employer match and the $72,000 ceiling—with those contributed dollars then moved to the sheltered side.
    • Your employer’s 401(k) must allow both after-tax non-Roth contributions AND in-plan conversions or in-service withdrawals—most plans do not.
    • The IRS confirmed this strategy is legal in Notice 2014-54, and it remains fully available in 2026.

    What Is the Mega Backdoor Roth and Why Does It Matter?

    The mega backdoor strategy is not a loophole—it is an IRS-approved method for moving after-tax money into a sheltered account within your 401(k) structure. The IRS codified the rules in Notice 2014-54, which explicitly permits employees to contribute after-tax dollars to a 401(k) and then move those dollars into a designated voluntary sub-account. The strategy has been operating in the open for over a decade, and no legislation has moved to eliminate it. High earners who are already maxing their regular standard deferral can use it to gain access to a substantially larger sheltered bucket than the $24,500 employee limit allows.

    The arithmetic is what makes this compelling. In 2026, the overall IRC §415(c) limit—covering all contributions to a defined contribution plan from all sources—is $72,000. If you contribute $24,500 in employee deferrals and your employer adds, say, $12,000 in matching contributions, that leaves $35,500 of headroom under the $72,000 ceiling. Voluntary after-tax contributions can fill some or all of that gap. Once those contributed dollars are in the retirement account, you shift them to the sheltered side—either through an in-plan conversion or by rolling them to an IRA via an in-service withdrawal. From that point forward, the money grows free of ordinary income levies for life. There are no required minimum distributions on these accounts during the owner’s lifetime, and qualified distributions are fully exempt from income tax.

    How the Math Works: Calculating Your Mega Backdoor Space

    Your available mega backdoor space depends on how much of the $72,000 annual ceiling is consumed by your regular contributions and your employer’s contributions. The formula is simple: $72,000 minus everything else equals your remaining voluntary capacity.

    Mega Backdoor Capacity: Example Calculation (2026)
    Contribution Component Example Amount Notes
    Employee base deferral $24,500 Pre-tax or designated Roth
    Catch-up (age 50–59, 64+) $8,000 Tax-now only if income over $145,000
    Employer match (example) $12,000 Varies by employer
    Total contributions so far $44,500
    2026 overall limit IRC §415(c) $72,000
    Voluntary space remaining $27,500 $72,000 minus $44,500

    That $27,500 goes in as after-tax non-Roth contributions, then transfers to the tax-free side through an in-plan conversion or an in-service withdrawal rolled to the IRA.

    What Your Plan Must Allow: Two Required Features

    The mega backdoor strategy requires two specific plan features that are distinct from ordinary designated 401(k) elections. Many plans offer one but not both, and some offer neither. Before investing any time in this, you must confirm that your specific plan document permits both capabilities.

    Required 401(k) Features for the Mega Backdoor Strategy
    Feature What It Means How Common?
    After-tax non-Roth contributions The ability to contribute dollars beyond your elective deferral limit into a separate voluntary bucket within the 401(k)—distinct from the designated after-tax sub-account Minority of plans; more common at large employers
    In-plan conversion The ability to shift voluntary non-Roth balances to the sheltered side within the same plan without leaving the employer Less common than voluntary contributions; often added separately
    In-service withdrawal The ability to roll voluntary non-Roth balances to a sheltered IRA while still employed; an alternative when in-plan conversion is unavailable Uncommon; the retirement account must explicitly permit distributions while employed
    If your employer’s 401(k) allows voluntary after-tax contributions but not in-plan conversions or in-service withdrawals, those contributed dollars sit earning taxable growth until you leave the employer. The opportunity to shift them to the sheltered side only opens at separation.

    How to Find Out If Your Plan Qualifies

    • Download the Summary Plan Description (SPD) and search the document for the phrase “after-tax contributions.” The SPD is a plain-language summary of the retirement account rules available from your HR department or benefits administrator’s website. If “after-tax contributions” does not appear, the account likely does not permit them.
    • Call your benefits administrator and ask two specific questions: (1) “Does my 401(k) allow after-tax non-Roth contributions beyond the elective deferral limit?” and (2) “Does it allow in-plan conversions or in-service withdrawals of voluntary amounts while I am still employed?” Both must be answered yes for the full strategy to work.
    • When rolling over, request a direct rollover—never a cash distribution. If the employer sends you a check, it is required to withhold 20% for federal withholding, even on after-tax dollars. You then have 60 days to roll the full amount—including the withheld 20% from other funds—to the sheltered IRA, or the payout is treated as ordinary income.

    In-Plan Conversion vs. Rollover to Roth IRA

    In-Plan Conversion vs. In-Service Rollover to Roth IRA
    Factor In-Plan Conversion In-Service Rollover to Roth IRA
    Where money lands Stays inside the 401(k) as a designated after-tax balance Moves to the IRA outside the employer’s account
    Requires leaving employer No No, if the account allows in-service withdrawals
    Withholding risk None—stays in the 401(k) Risk of 20% withholding if not direct rollover
    Roth IRA income limits apply No No—rollovers are not subject to IRA contribution income limits
    Investment control Limited to the 401(k) investment menu Unlimited—any investment available in your Roth IRA
    Access before 59½ Subject to the account’s distribution rules IRA contribution basis is accessible anytime; earnings have 5-year + age rules

    High earners above $161,000 (single) or $240,000 (married filing jointly) cannot make direct contributions to a sheltered IRA due to income limits. Rolling over voluntary after-tax 401(k) amounts to the IRA sidesteps this restriction entirely. Notice 2014-54 explicitly confirms that when a 401(k) distributes a mix of after-tax and pre-tax amounts, the employee can direct the contributed portion to the sheltered IRA and the pre-tax portion to a traditional IRA—the two do not have to go to the same destination.

    Tax Consequences and the Convert-Early Rule

    Voluntary after-tax non-Roth contributions have already been taxed as ordinary income, so you do not owe additional levy on the principal when you shift it. You owe ordinary income charges only on any earnings that accumulated in the voluntary bucket before the transfer. If you contribute $5,000 in January and move it in March, the amount owed might be $20 in interest—essentially negligible. The problem grows when you let these contributed dollars sit for months or years: the compounding gains turn a clean move into a meaningful bill.

    The pro-rata rule—which applies when you roll a traditional IRA to a sheltered account and have pre-tax IRA balances elsewhere—does not apply here. Notice 2014-54 clarified that a direct rollover of voluntary 401(k) amounts to the sheltered IRA is treated as coming entirely from contributed dollars. You are not forced to blend pre-tax and contributed portions in proportion. This is a significant distinction from the ordinary backdoor IRA strategy, which can be complicated by existing IRA balances.

    Shift funds early and frequently—ideally the same quarter you contribute. Gains in the voluntary bucket compound and make future transfers more expensive.

    Record-Keeping: Non-Negotiable

    You must track your voluntary after-tax cost basis separately from all other 401(k) balances. Your benefits administrator tracks this internally, but you should verify it annually against your year-end account statement. If you roll these amounts to the IRA, you must file Form 8606 with your federal return to report the nontaxable portion of the rollover. Failure to file Form 8606 can result in double-counting at distribution. Keep records indefinitely—IRS statute of limitations does not protect you if you cannot prove the basis.

    The Roth Five-Year Clock for Conversions

    Each in-plan transfer starts its own five-year holding period. This matters for earnings access before age 59½: if you withdraw earnings from a transferred amount before both five years have passed and you have reached 59½, you may owe ordinary income levies and a 10% penalty on those earnings. Contributions you made directly—not transfers—are always accessible penalty-free at any time, because you already paid the levy on them. The five-year rule applies only to earnings.

    The practical solution is to open the sheltered IRA as early as possible, even if you fund it with a small amount—$1 qualifies. The five-year clock starts on January 1 of the year for which you make the first contribution. An account opened and funded in 2026 starts its clock on January 1, 2026. If you roll mega backdoor funds into that account in 2030, the earnings clock is already four years old. This small early action can save years of waiting.

    Before You Start: 5 Things to Verify

    • Your employer’s 401(k) allows after-tax non-Roth contributions. Download the Summary Plan Description or call your benefits administrator and ask explicitly. This is the first gate — the strategy does not exist if this feature is absent.
    • In-plan conversion or in-service withdrawal is available. Without one of these, voluntary contributions sit accumulating taxable earnings until you separate from your employer. Both questions must be answered yes for the full strategy to work while employed.
    • Your voluntary contribution space is calculated correctly. The formula is $72,000 minus your planned employee deferral (including any catch-up) minus your estimated employer match. Update this each year as employer contributions change.
    • You have a sheltered IRA open and funded, even minimally. Opening the account early starts the five-year clock on January 1 of that year. Rolling mega backdoor funds into an established IRA that is already years old avoids waiting on the earnings clock entirely.
    • You have a transfer and record-keeping plan in place. Move funds quarterly to minimize taxable gains sitting in the voluntary bucket. File Form 8606 every year you complete a rollover. Keep basis records indefinitely — the IRS has no statute of limitations if you cannot prove basis at distribution.

    Bottom line: The mega backdoor strategy delivers the most value to high earners who are already maxing their standard 401(k) deferral, whose employer specifically supports both required features, and who are willing to manage quarterly fund movements and annual Form 8606 filings. It is not a passive set-and-forget approach — it requires annual attention to payroll elections, transfer timing, and basis tracking. For eligible participants who are disciplined about execution, it opens a sheltered savings pathway that is many times larger than the standard IRA limit allows.

    Honest boundary: Not every employer supports this strategy. The mega backdoor approach has been legal since at least 2014 but depends entirely on your specific plan’s terms. Verify with your benefits administrator and a tax professional. This is not financial or tax advice.
  • Mandatory Roth Catch-Up 2026: What High Earners Must Know

    Mandatory Roth Catch-Up 2026: What High Earners Must Know

    401(k) · SECURE 2.0 · 2026
    • Workers 50+ who earned over $145,000 from a single employer in 2025 must make all 2026 additional deferrals as Roth—pre-tax is no longer an option for them.
    • The standard extra deferral for ages 50–59 and 64+ is $8,000. Workers aged 60–63 qualify for a new “super” amount of $11,250 under SECURE 2.0.
    • If your plan has no designated Roth feature, the extra contribution is blocked entirely in 2026—$0 allowed, regardless of income.
    • The IRS finalized this rule in January 2025 after a two-year grace period. There is no further delay.

    What Did SECURE 2.0 Actually Change?

    The SECURE 2.0 Act, signed December 29, 2022, rewrote the rules for age-50-plus deferrals effective January 1, 2026. For decades, workers could add an extra $7,500 pre-tax to their 401(k) on top of the base limit. That option survives—but only for earners at or below the $145,000 threshold.

    Above that wage level, every extra dollar must go into a designated Roth account. You pay ordinary income on the contributed amount now. The money then grows exempt from further levy, and qualified withdrawals in retirement are fully sheltered as well.

    Why the Two-Year IRS Delay?

    The IRS issued Notice 2023-62 suspending enforcement until December 31, 2025. Plans needed time to update payroll systems, and many small employers had never offered a designated voluntary sub-account inside their 401(k). Starting January 1, 2026, the new rule is fully in effect with no further grace period.

    Who Is Affected: The $145,000 Threshold

    The test looks back one year. Your employer checks your FICA wages (W-2 Box 3 or Box 5) from 2025—only from that single employer. Two employers each paying $100,000 = neither triggers the requirement. One employer paying $180,000 = mandatory pay-now treatment in 2026 on every extra dollar you defer.

    Catch-Up Rules by Income Level (2026)
    2025 FICA Wages (Single Employer) Ages 50–59 & 64+ Ages 60–63 Treatment
    $145,000 or less Up to $8,000 Up to $11,250 Pre-tax or Roth — your choice
    Over $145,000 Up to $8,000 Up to $11,250 Roth only — no exceptions
    Any income, plan has no designated after-tax feature $0 $0 Extra deferrals blocked entirely
    Note: The $145,000 threshold is indexed to inflation and will adjust annually. Verify the current figure at IRS.gov before making your 2026 election.

    2026 Contribution Limits: The Full Picture

    2026 401(k) Contribution Limits
    Contribution Type Age Group 2026 Limit
    Base employee deferralUnder 50$24,500
    Standard catch-up50–59 and 64+$8,000
    Super catch-up (SECURE 2.0)60, 61, 62, 63$11,250
    Total employee max (ages 60–63)60–63$35,750
    Overall limit (all sources)Any age$72,000
    Super catch-up window is exactly four years. The year you turn 64, the limit drops back to $8,000. Workers born in 1963–1966 are in the sweet spot for the 2026 super catch-up.
    Catch-Up Contribution Limits 2024–2026 by Year and Earner Type Catch-Up Contribution Limits: 2024 → 2026 Ages 50+ only. Base deferral ($24,500) not shown. Catch-Up Limit ($) $0 $4k $8k $10k $12k $7,500 2024 Any earner Standard $7,500 2025 Grace period Standard OK $8,000 2026 ≤$145k income Standard or contributed $8,000 2026 >$145k income After-tax ONLY $11,250 2026 Ages 60–63 Super add-on Standard or contributed (earner’s choice) Contributed mandatory (>$145k) Super add-on deferral (ages 60–63)

    Tax Impact: Paying Now vs. Paying Later

    Forcing high earners into pay-now treatment shifts when the IRS collects. Standard deferrals delay ordinary income levy until withdrawal—still a useful strategy if you expect lower rates in retirement. The designated voluntary sub-account approach means settling up in the contribution year, but every dollar—including all investment growth—exits completely sheltered in retirement.

    Pre-Tax vs. Mandatory Roth Catch-Up: Key Differences
    Factor Pre-Tax Catch-Up Mandatory Roth Catch-Up
    Levy in contribution yearNone on contributionOrdinary income applies
    Growth subject to levy?Yes, at withdrawalNo (qualified distribution)
    Lifetime mandatory withdrawalsRequired starting at 73None from designated after-tax 401(k)
    Heirs benefit?Heirs pay ordinary incomeHeirs inherit sheltered
    Available to earners over $145k?No — from 2026Yes

    What If Your Plan Has No Roth Option?

    Critical: If your employer’s plan has no designated after-tax sub-account feature, workers earning over $145,000 cannot make any additional deferrals in 2026—neither sheltered nor pre-tax. The limit is $0. Verify your plan’s options before your first paycheck of 2026.

    Employers who wanted to preserve the age-50-plus add-on for high earners had to amend their plan to include a designated after-tax sub-account by January 1, 2026. If yours still lacks one, you have two paths: maximize the base $24,500 deferral, and separately consider a backdoor Roth IRA strategy outside the plan (if eligible or via pre-tax-to-voluntary conversion).

    State Tax: The Extra Layer

    Most states conform to federal treatment: you pay state income levy on the contributed amount now and owe nothing on qualified distributions in retirement. California (13.3% top rate) and New York add meaningfully to the upfront cost of this mandatory pay-now approach. States like Nevada, Texas, and Florida have no income levy at all—every dollar of future qualified distributions stays in your pocket.

    Action Checklist

    1. Check your 2025 FICA wages from each employer. If any single employer paid you more than $145,000, all additional 2026 deferrals must use pay-now treatment in the designated after-tax sub-account.
    2. Verify your plan has a designated after-tax feature. Log in to your 401(k) portal or call HR. No such option = no extra deferrals at all for high earners in 2026.
    3. Confirm your age group. Turn 60–63 in 2026? Your extra deferral limit is $11,250, not $8,000—a $3,250 difference worth checking.
    4. Update your payroll deferral election to reflect the new limits. For ages 60–63 maxing out: $24,500 base + $11,250 = $35,750 total employee contribution.
    5. Run a 2026 income projection with your CPA. Pay-now treatment means higher taxable income this year—ensure withholding or estimated payments cover the gap.
    6. Review beneficiary designations on the after-tax sub-account—it may appear separately from your standard balance in the portal.
    7. If your plan lacks the after-tax designation option, ask HR immediately—adding the feature requires a formal plan amendment and takes time to implement.
    Honest boundary: The $145,000 wage threshold adjusts for inflation each year. All figures reflect IRS guidance as of early 2026. Confirm current limits at IRS.gov or with your benefits department before making elections. This article is not financial or legal advice.